
You can trade crowded suburbs for serene shorelines without draining your nest egg. Across the country, several scenic lakefront towns offer waterfront properties at prices well below the national median.
While national waterfront homes average over $530,000, smart retirees find genuine bargains in regions with affordable waterfront living. Many hidden gems feature active boating communities, nearby healthcare, and generous state tax perks.
By targeting affordable lake communities, you can stretch your fixed income while enjoying peaceful mornings by the water. Explore ten remarkable locations where comfortable waterfront retirement living remains within reach.
The Financial Appeal of Waterfront Retirement Living
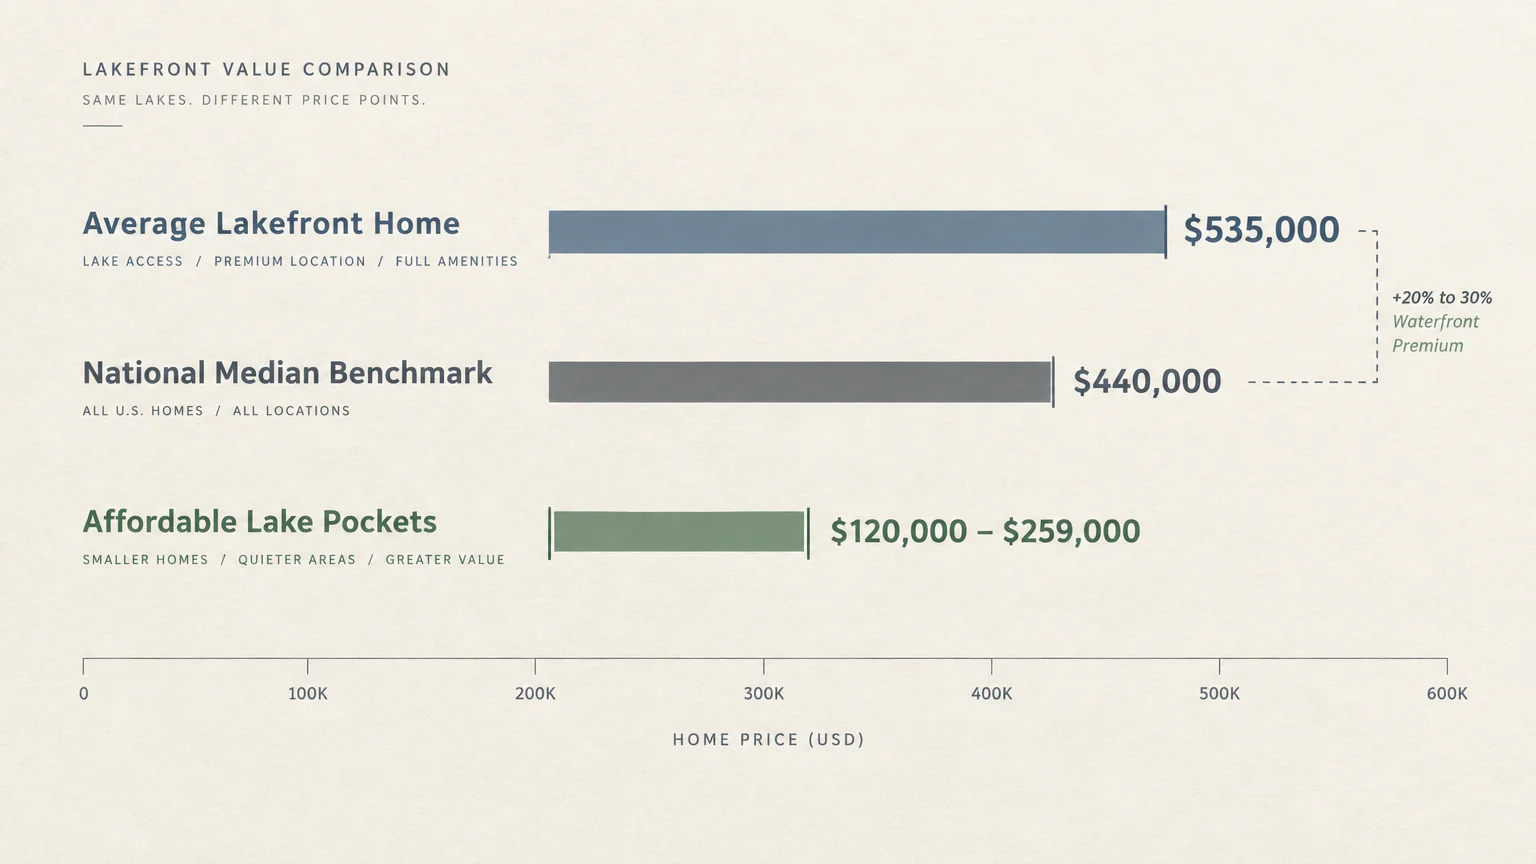
Living by the water has long represented the ultimate American retirement dream. Historically, however, waterfront real estate carries an average price premium of 20% to 30% over inland properties.
According to national market reports from Lake Homes Realty, the average listing price for lake-adjacent homes hovers around $535,000. That figure places many coastal and resort destinations out of reach for retirees on fixed budgets.
Fortunately, you do not need millions to wake up next to a pristine shoreline. Several pockets throughout the Midwest, the South, and the Northeast feature median prices well beneath the national home benchmark of $440,000.
Choosing an affordable lake market allows you to preserve your retirement nest egg. You can redirect your hard-earned savings toward travel, hobbies, and everyday living expenses rather than an inflated mortgage.
When selecting a town, you should also evaluate state income taxes, local property taxes, and regional healthcare access. Finding the right balance ensures that your dream retreat remains financially sustainable for decades.
“The goal isn’t more money. The goal is living life on your terms.” — Jean Chatzky, Financial Journalist
10 Affordable Lake Retirement Communities
We analyzed home prices, everyday living expenses, and tax policies to identify top lake retirement towns across America. These ten towns combine accessible housing markets with abundant recreation and practical amenities.
1. Rogers City, Michigan (Lake Huron)
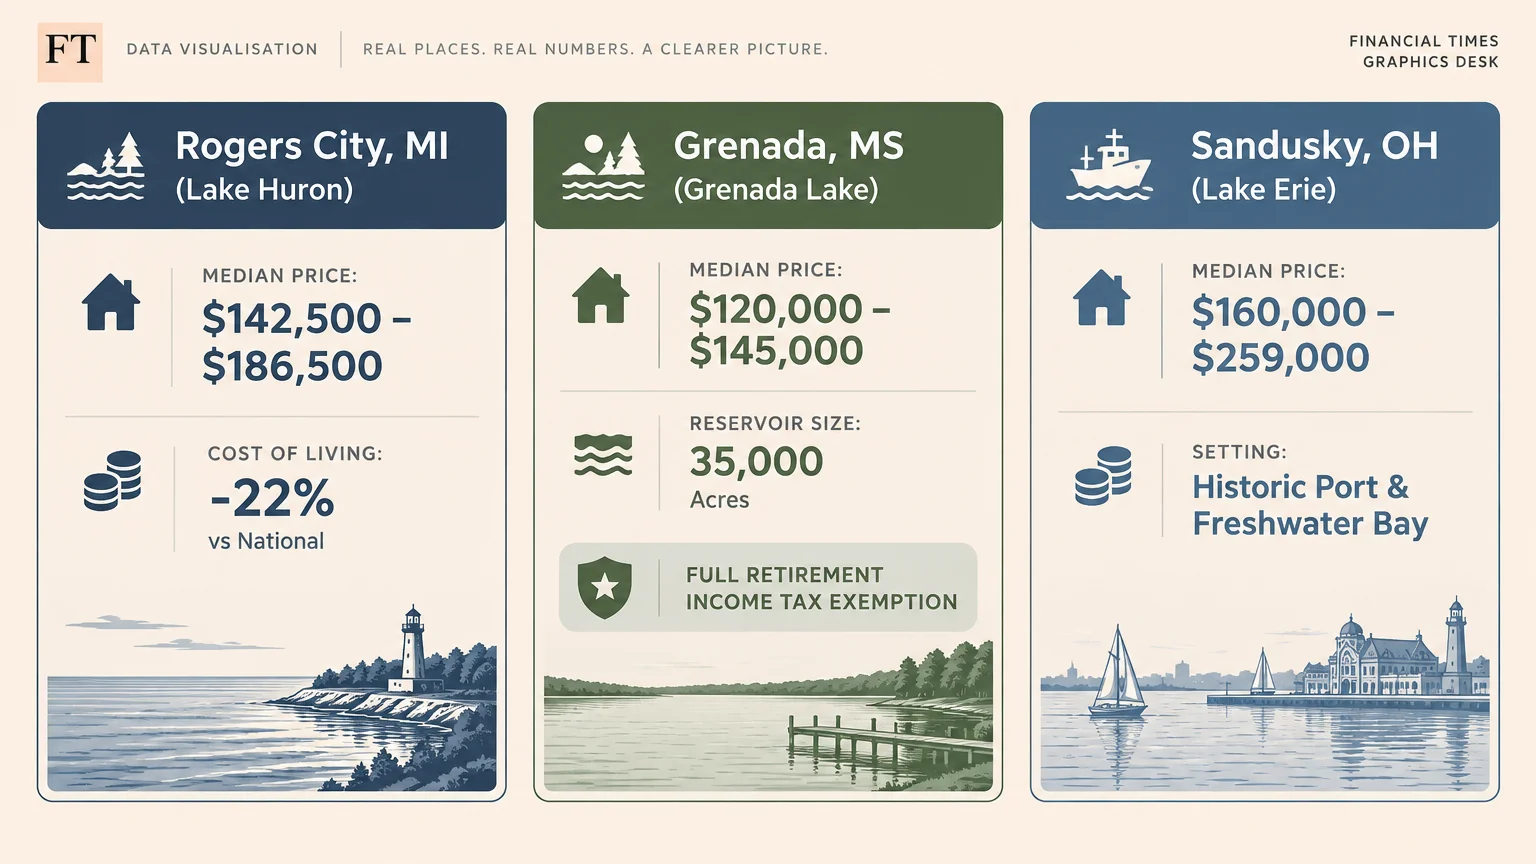
Rogers City sits peacefully along the northern shores of Lake Huron in Michigan’s Presque Isle County. The community frequently ranks as one of the most affordable freshwater destinations in the United States.
Median home list prices range between $142,500 and $186,500, offering exceptional value for Great Lakes access. Furthermore, the overall cost of living sits approximately 22% below the national baseline.
Retirees enjoy a relaxed maritime pace centered on the local marina and historic 40 Mile Point Lighthouse. Paved lakeside trails, uncrowded salmon fishing, and cool summer breezes make it an outdoor haven.
2. Grenada, Mississippi (Grenada Lake)
Grenada sits near the edge of Grenada Lake, an expansive reservoir spanning over 35,000 acres. Anglers know the area as one of the top crappie-fishing destinations in North America.
You can find lake-adjacent homes selling between $120,000 and $145,000. These price levels establish Grenada as one of the lowest-cost waterfront markets in the entire nation.
Mississippi also provides outstanding tax treatment for retirees. The state fully exempts qualified retirement income, including pensions, 401(k) distributions, and Social Security benefits, from state personal income tax.
3. Sandusky, Ohio (Lake Erie and Sandusky Bay)
Sandusky sits along the southern shore of Lake Erie, offering freshwater living at a fraction of coastal costs. It serves as an active port town with rich architecture and deep maritime traditions.
Median home prices hover between $160,000 and $259,000. This pricing lets you purchase lakefront homes for retirees without taking on substantial mortgage debt.
Healthcare access is a key strength here. The community houses Firelands Regional Medical Center, which offers specialized inpatient and outpatient care tailored to senior wellness.
4. Hot Springs, Arkansas (Lake Hamilton and Lake Ouachita)
Hot Springs blends dramatic Ouachita Mountain views with easy access to Lake Hamilton and Lake Ouachita. The area has welcomed health-seeking retirees for generations thanks to its historic natural thermal baths.
Area homes typically list between $245,000 and $255,000. You can choose between established waterfront condominiums and quiet single-family homes nestled inside protected coves.
Arkansas does not levy state income tax on your Social Security benefits. Additionally, the state grants an individual retirement income exemption of up to $6,000 annually for employer-sponsored pensions.
5. Sebring, Florida (Lake Jackson)
Sebring surrounds the circular shores of Lake Jackson in central Florida’s Highlands County. It provides year-round sunshine without the extreme congestion or price inflation of coastal Florida metros.
Average home values range between $241,000 and $250,000. This market represents rare affordability for retirees seeking sunshine and freshwater boating.
Florida charges 0% state personal income tax, shielding your retirement withdrawals and pensions completely. Seniors can review housing counseling resources through the U.S. Department of Housing and Urban Development (HUD) when purchasing here.
6. Kimberling City and Branson, Missouri (Table Rock Lake)
Kimberling City sits directly on the shores of Table Rock Lake, just minutes from the live theaters of Branson. The lake features nearly 800 miles of clear shoreline and deep, clean water.
Median listing prices in the area sit between $205,000 and $250,000. Retirees can easily find low-maintenance condominiums featuring deeded community boat slips.
Missouri enacted legislation fully exempting Social Security benefits from state income taxes. This statutory exemption provides meaningful savings for households managing standard monthly retirement incomes.
7. Mountain Home, Arkansas (Bull Shoals Lake and Norfork Lake)
Mountain Home sits cradled between Norfork Lake and Bull Shoals Lake in the northern Arkansas Ozarks. Combined, these twin reservoirs offer over 1,000 miles of scenic shoreline.
Median listing prices range between $175,000 and $215,000. Modest property tax assessments in Baxter County keep your recurring annual carrying costs very low.
The region also boasts world-class fly fishing along the Norfork and White Rivers. Local medical facilities provide robust cardiology and orthopedic services to support your active lifestyle.
8. Jamestown, New York (Chautauqua Lake)
Jamestown borders the southern waters of Chautauqua Lake in western New York. It stands out as one of the most accessible lake retirement towns in the northeastern United States.
Median listing prices frequently fall below $130,000, with many modest cottages selling between $70,000 and $110,000. Cultural lectures and classical concerts at the nearby Chautauqua Institution enrich your summers.
New York exempts Social Security benefits from state taxation. Furthermore, eligible residents age 59½ and older can exclude up to $20,000 in qualifying private pension distributions each year.
9. Albert Lea, Minnesota (Fountain Lake and Albert Lea Lake)
Albert Lea rests among the prairie lakes of southern Minnesota, centering life around Fountain Lake and Albert Lea Lake. The community is an early adopter of healthy living Blue Zones initiatives.
Median listing prices range between $160,000 and $195,000. This pricing provides Upper Midwest lake living at roughly 55% below the national median home value.
The city maintains miles of paved shoreline walking paths, accessible kayak docks, and disc golf courses. Community-focused senior programs help you stay active and socially connected throughout every season.
10. Guntersville, Alabama (Lake Guntersville)
Guntersville occupies a peninsula surrounded by 69,000 acres of Lake Guntersville’s premier bass fishing waters. The town offers a relaxed southern pace framed by the Appalachian foothills.
Median listing prices hover between $290,000 and $340,000, though smaller inland-access cabins sell for considerably less. You will find state park lodges, golf courses, and peaceful marinas close by.
Alabama boasts an effective property tax rate of roughly 0.40%, among the lowest nationwide. The state also exempts Social Security benefits and qualified defined-benefit pensions from individual income taxes.
Comparison Table: Affordable Waterfront Towns at a Glance
Evaluating communities side-by-side helps you prioritize home values alongside tax perks and outdoor recreation. The table below outlines key financial metrics for these ten budget-friendly destinations.
| Community & Lake | Median Home Listing Price | Key State Tax Advantage | Primary Lifestyle Feature |
|---|---|---|---|
| Rogers City, MI (Lake Huron) | $142,500 – $186,500 | State exemption for retirement income up to set caps | Quiet Great Lakes harbor & salmon fishing |
| Grenada, MS (Grenada Lake) | $120,000 – $145,000 | 100% exemption on pensions, 401(k)s, and Social Security | World-class crappie fishing & mild winters |
| Sandusky, OH (Lake Erie) | $160,000 – $259,000 | Graduated state income tax with senior tax credits | Island ferry access & regional medical centers |
| Hot Springs, AR (Lake Hamilton) | $245,000 – $255,000 | No tax on Social Security; $6,000 pension deduction | Historic thermal bathhouses & mountain trails |
| Sebring, FL (Lake Jackson) | $241,000 – $250,000 | 0% state personal income tax | Year-round warm climate & golf courses |
| Kimberling City, MO (Table Rock Lake) | $205,000 – $250,000 | 100% tax exemption for Social Security benefits | Clear mountain water & Branson entertainment |
| Mountain Home, AR (Bull Shoals / Norfork) | $175,000 – $215,000 | No tax on Social Security; low property taxes | Trout river fishing & twin reservoir boating |
| Jamestown, NY (Chautauqua Lake) | Under $130,000 | No tax on Social Security; $20,000 pension exclusion | Chautauqua Institution culture & arts |
| Albert Lea, MN (Fountain Lake) | $160,000 – $195,000 | Social Security income subtractions for modest brackets | Lakeside trails & Blue Zones community wellness |
| Guntersville, AL (Lake Guntersville) | $290,000 – $340,000 | Low property taxes (~0.40%); pension exemptions | Expansive bass boating & mountain scenery |
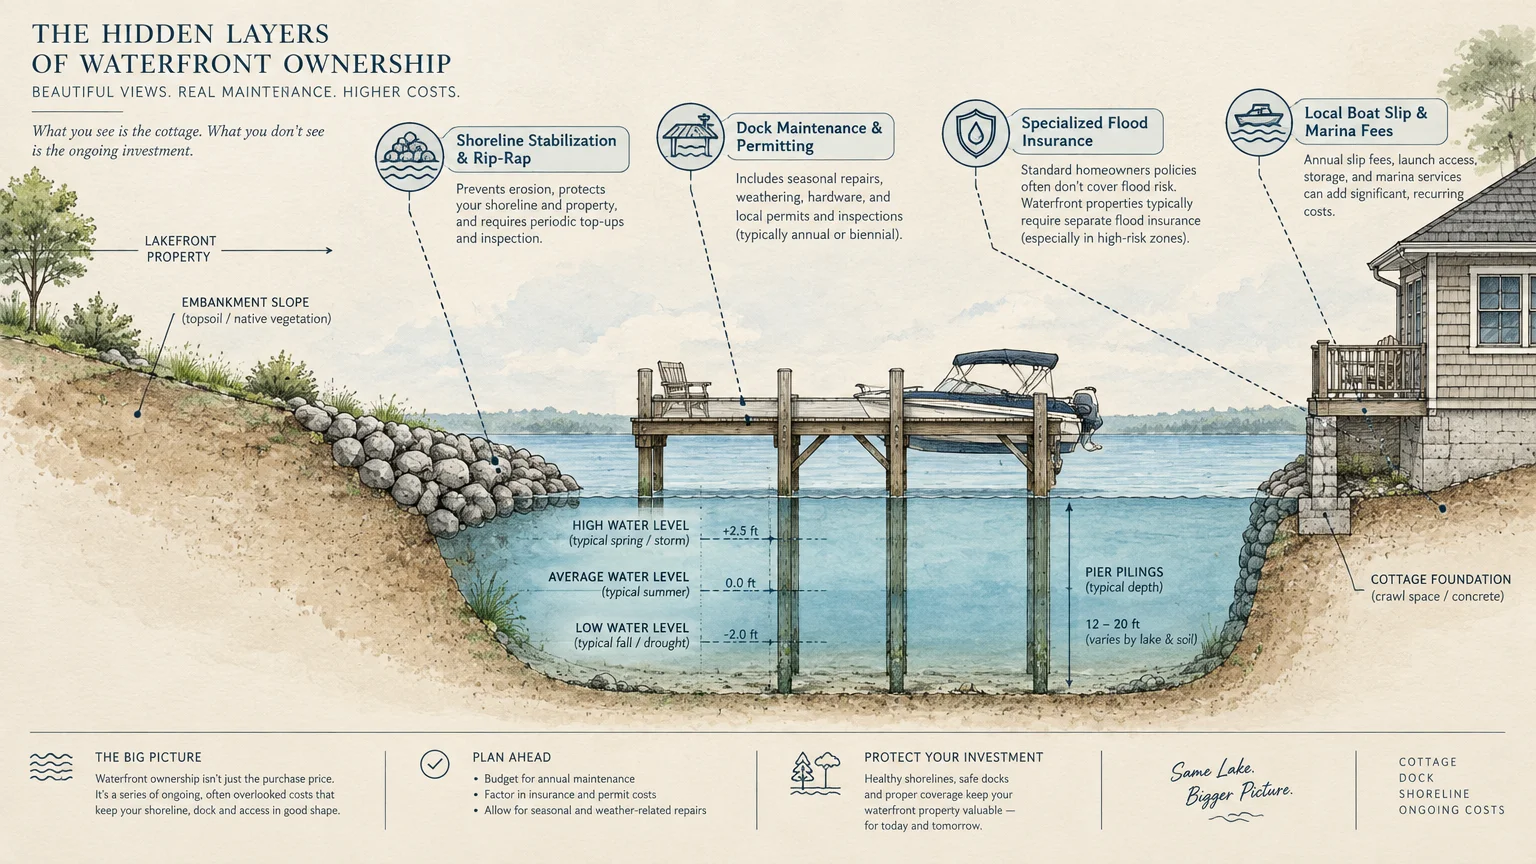
Evaluating True Waterfront Costs: Beyond the Purchase Price
The initial purchase price only tells part of the story when buying lake property. You must account for additional carrying costs unique to shoreline living before finalizing your budget.
Waterfront parcels frequently sit within designated Special Flood Hazard Areas mapped by FEMA. If you secure a mortgage, federal guidelines require flood insurance policies through the National Flood Insurance Program.
Flood coverage premiums typically add between $800 and $3,000 to your annual living costs. Review official risk maps carefully before placing an offer on any low-lying property.
Dock ownership introduces separate fees and regulatory responsibilities. Most reservoirs managed by the U.S. Army Corps of Engineers or utility companies charge annual or multi-year shoreline use permits.
Permit fees generally range from $50 to several hundred dollars per renewal cycle. You must also budget for dock flotation maintenance, cable replacements, and seasonal decking treatments.
Finally, examine homeowner association or property owner association dues. Master-planned lake subdivisions often levy annual fees between $600 and $4,000 to maintain private community boat ramps and marinas.
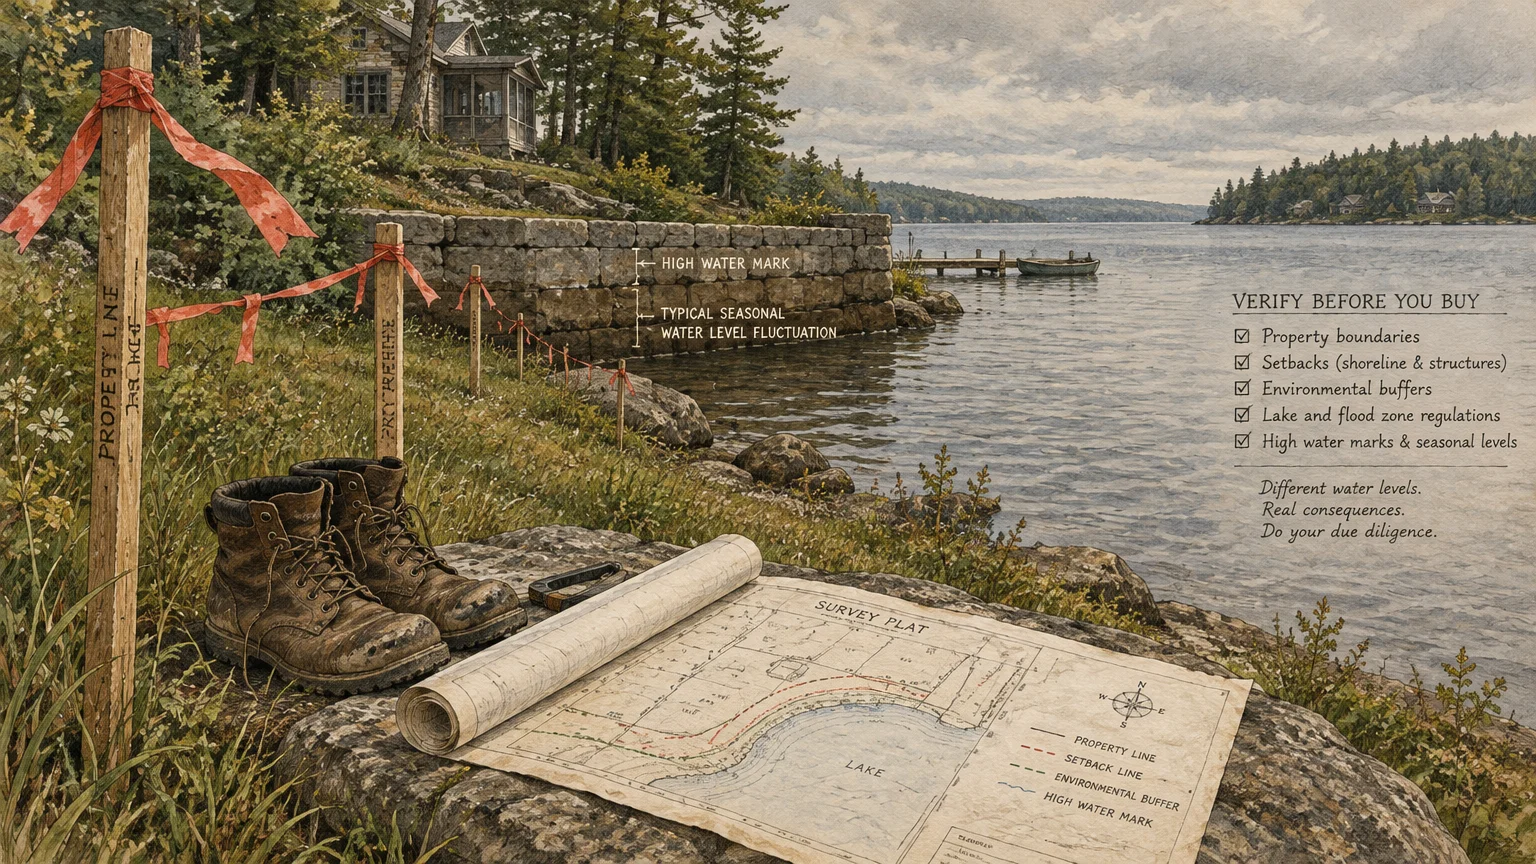
Common Mistakes to Avoid When Buying Lakefront Property
Purchasing a lake home involves different physical and legal inspections than buying a suburban tract house. Avoiding common missteps will protect both your savings and your peace of mind.
- Ignoring seasonal water fluctuations: Many reservoirs drop ten to twenty feet during winter drawdowns. Confirm that your prospective boat slip retains usable water depth during late summer and fall.
- Skipping specialized structural inspections: Shoreline humidity accelerates wear on foundations, decks, and outdoor plumbing. Always hire an inspector experienced in evaluating bulkhead integrity and waterfront bulkheads.
- Overlooking deeded access rules: An off-water house advertised as a lake retreat may only include community easements. Verify whether your access rights are legally deeded or merely casual neighborhood arrangements.
- Failing to review local rental rules: If you plan to rent out your cottage part-time, review municipal short-term rental bans. Many lake towns now strictly limit vacation rentals in residential zones.
Before applying for financing, you can review mortgage affordability tools published by the Consumer Financial Protection Bureau (CFPB). Sound loan terms protect your budget from rising interest rates.
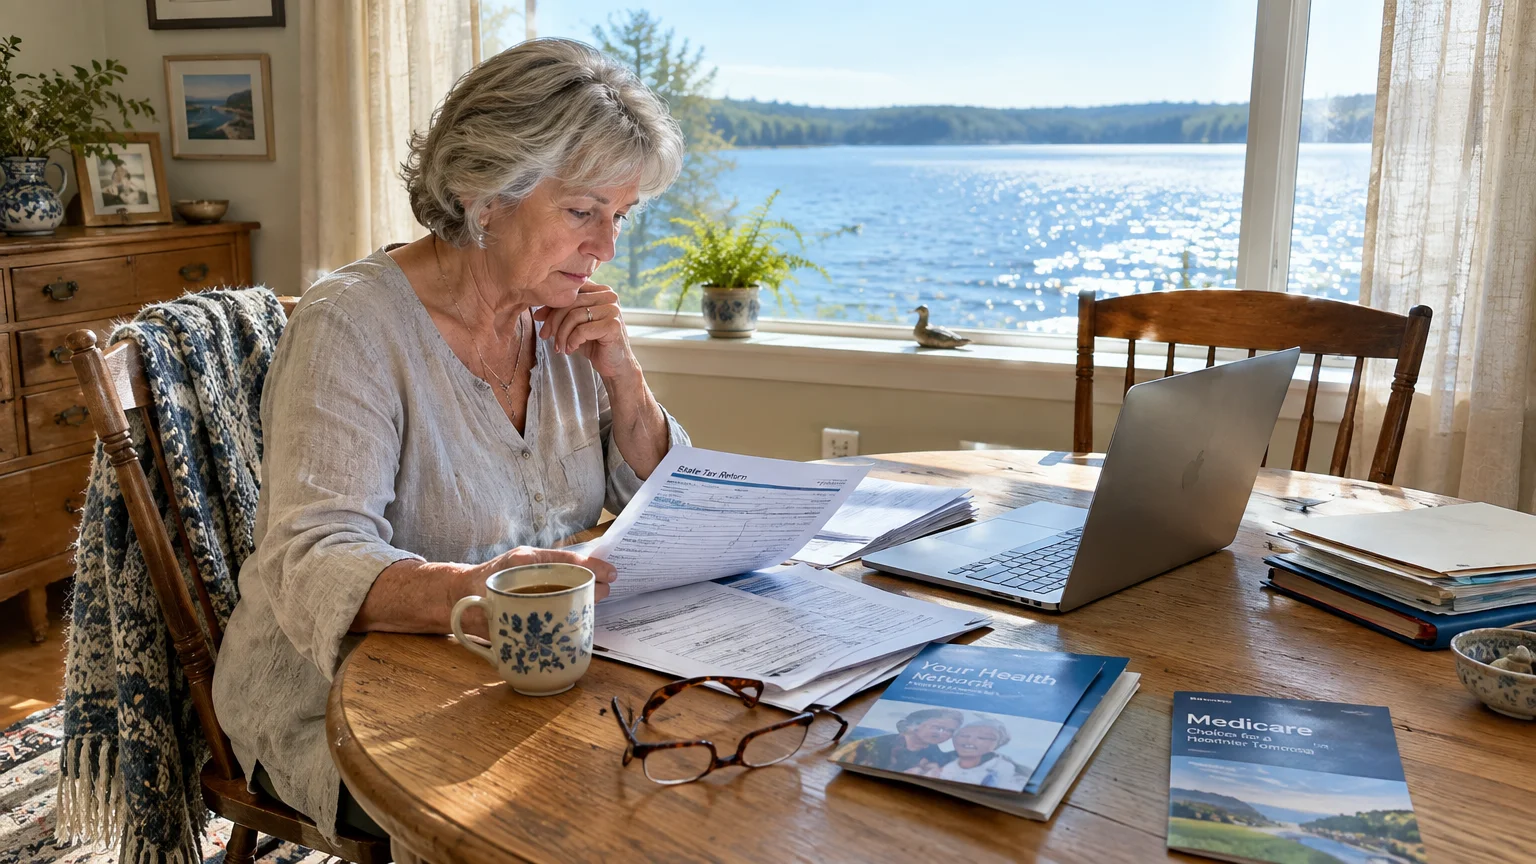
Tax Planning and Healthcare Proximity for Lake Living
Your geographic location significantly influences your net income during retirement. Moving to a state with favorable tax laws often offsets modest differences in home purchase prices.
States like Florida and Mississippi shield key income streams, allowing your portfolio distributions to stretch further. To understand how federal tax brackets interact with state laws, consult resources on the Internal Revenue Service (IRS) website.
Healthcare access requires equal scrutiny when you move away from major cities. Rural lake coves often sit thirty to forty-five minutes away from full-service emergency departments.
Check the distance from your target home to the nearest accredited regional hospital. You can evaluate provider networks and facility ratings directly through Medicare.gov before choosing a neighborhood.
Ensuring that primary care clinics and physical therapy centers operate nearby prevents medical visits from becoming exhausting day trips. Quality local healthcare keeps your retirement relaxing and secure.
“Retirement is not the end of the road. It is the beginning of the open highway.” — Suze Orman, Personal Finance Author
Frequently Asked Questions About Lake Retirement Towns
Can I really find waterfront homes under $200,000?
Yes, affordable lake communities across the Midwest and South feature homes priced under $200,000. Towns like Rogers City, Michigan, and Grenada, Mississippi, consistently offer standalone cottages at these accessible price points.
Are property taxes consistently higher on lakefront properties?
Waterfront homes usually carry higher assessed values than interior parcels, which can lead to higher total tax bills. However, buying in low-tax states like Alabama or Arkansas helps keep your total property tax payments very manageable.
What hidden expenses surprise first-time lakefront buyers?
Retirees are often surprised by dock maintenance expenses, shoreline stabilization mandates, and mandatory flood insurance premiums. Watercraft registration, seasonal winterization, and higher insurance riders also add to annual costs.
Does proximity to a lake affect my home insurance rates?
Yes, wind and water exposure can increase standard homeowners insurance rates. Properties located inside flood hazard zones also require separate flood policies that are not included under standard coverage.
Charting Your Course to the Water
Affordable waterfront living does not require unrealistic financial compromises. By focusing on overlooked markets with low property values and retiree-friendly tax rules, you can enjoy shorelines without jeopardizing your security.
Take time to visit your preferred communities during different seasons to observe weather, tourism patterns, and water levels. A leisurely exploratory trip provides the clearest view of daily life on the water.
This is educational content based on general financial principles for seniors. Individual results vary based on your situation. Always verify current benefit amounts, tax rules, and program eligibility with official government sources.
Last updated: February 2026. Benefit amounts, tax rules, and program details change annually—verify current figures with official government sources.
Leave a Reply