
Tossing aside a piece of Social Security mail can quickly jeopardize your monthly retirement or disability income. A single missed deadline often leads to withheld checks, lost benefits, or surprise financial penalties.
The Social Security Administration sends critical updates regarding eligibility reviews, payment adjustments, and overpayments through the postal system. Ignoring these notifications will never make the underlying issue disappear.
Acting immediately protects your cash flow and safeguards your hard-earned benefits against aggressive automated recovery rules. Learn which seven letters demand your immediate attention and how to respond safely.
1. Notice of Overpayment (Demand for Repayment)
A Notice of Overpayment informs you that the government paid you more benefits than you were legally eligible to receive. This notice demands immediate repayment of the excess balance.
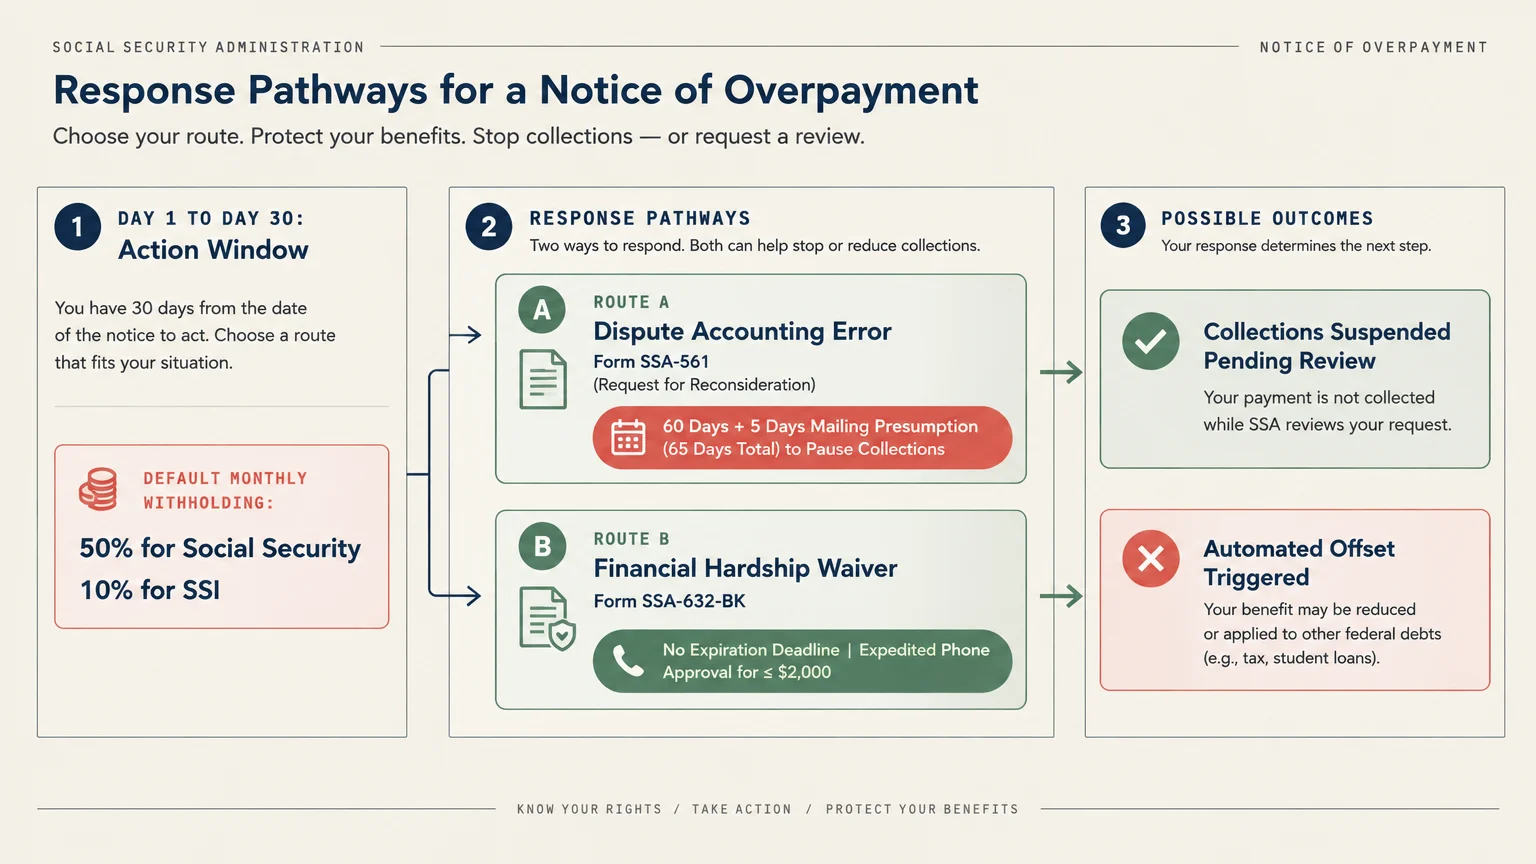
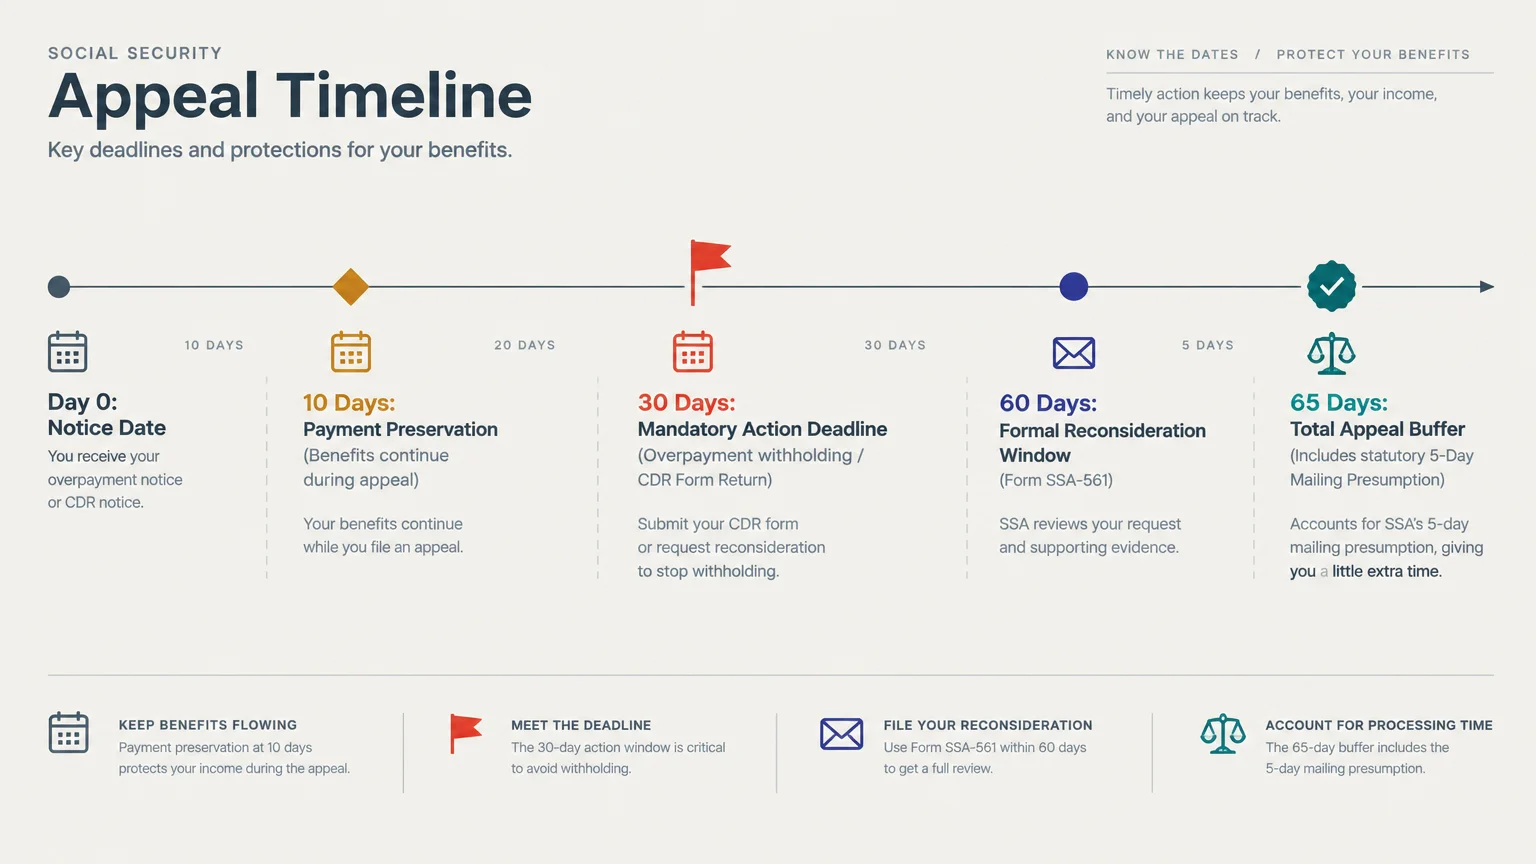
You have exactly 30 days from the date on the notice to respond before automated collections begin. Acting within this month-long window prevents the agency from reducing your monthly checks.
Under current policy, the default withholding rate for Social Security retirement and disability benefits is set at 50% of your monthly check. Supplemental Security Income (SSI) overpayments remain capped by law at 10%.
If you believe the agency made an accounting error, file Form SSA-561 (Request for Reconsideration) within 60 days. This formal dispute requires the agency to review your records for calculation mistakes.
Federal regulations presume you received the letter five days after the postmark date, granting an effective 65-day appeal deadline. Filing on time pauses all collection actions until the agency issues a formal review decision.
If the overpayment was not your fault and repaying it causes financial hardship, submit Form SSA-632-BK to request a waiver. Unlike an appeal, an overpayment waiver carries no strict expiration deadline.
For balances of $2,000 or less, the agency can often approve an administrative waiver over the phone without extensive documentation. Contact the Social Security Administration immediately to review your options.
2. Continuing Disability Review Notice (Forms SSA-455 and SSA-454)
If you receive Social Security Disability Insurance (SSDI) or SSI disability payments, the government periodically checks your medical eligibility. A Continuing Disability Review (CDR) notice signals that this mandatory evaluation has begun.
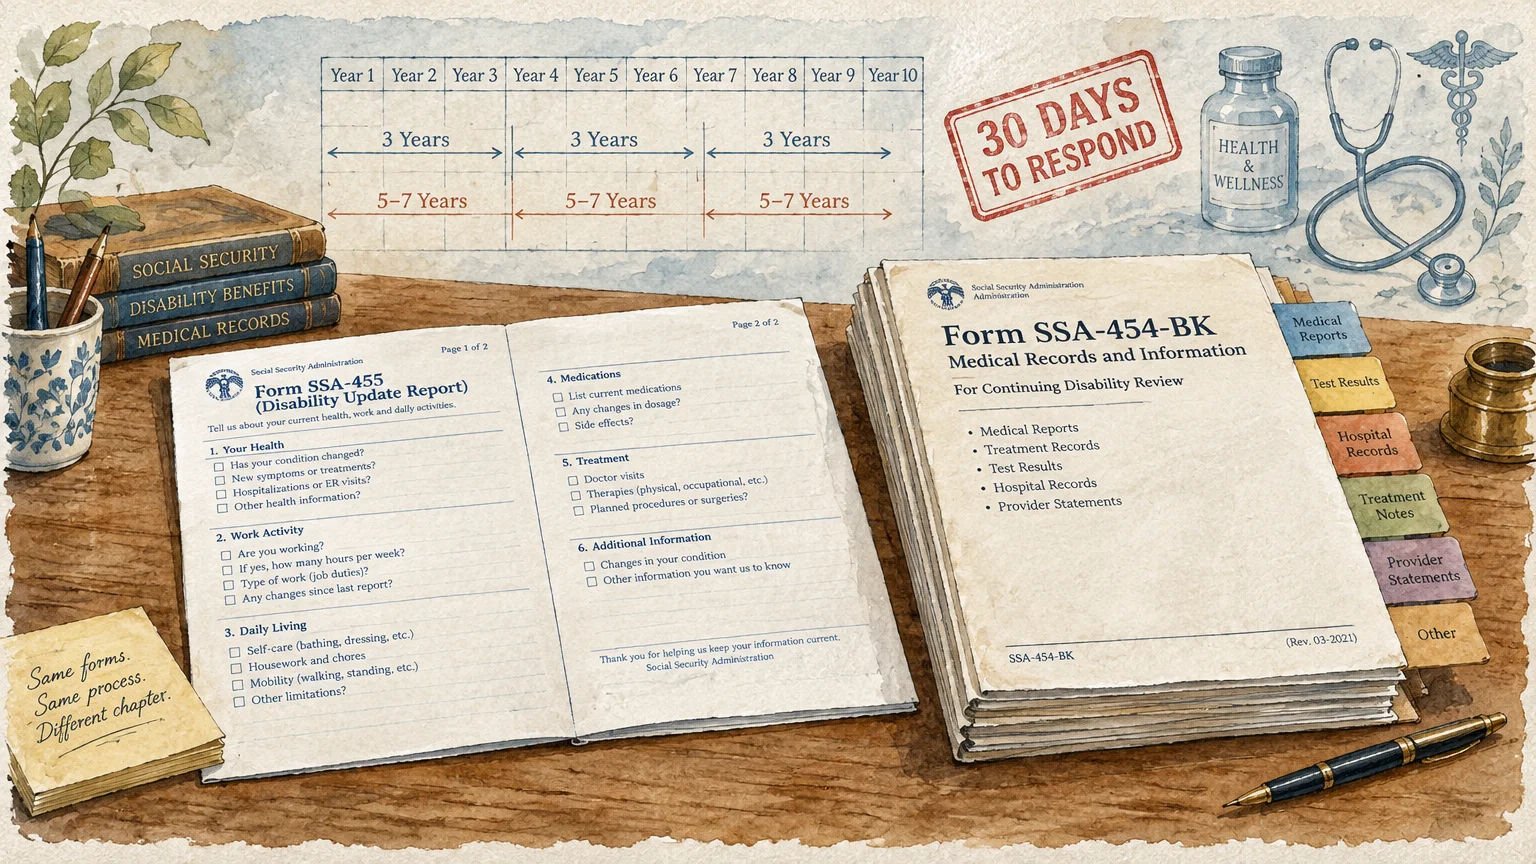
Beneficiaries receive one of two forms based on their medical history. You will receive either Form SSA-455 (Disability Update Report) or Form SSA-454-BK (Continuing Disability Review Report).
Form SSA-455 is a short two-page questionnaire that asks about recent doctor visits, treatments, and work activity. In contrast, Form SSA-454-BK requires a comprehensive summary of your medical records and diagnostic tests.
Routine medical reviews occur every three years if medical improvement is possible. When medical improvement is unlikely, evaluations happen every five to seven years instead.
You must complete and return these forms within the specified deadline, which is typically 30 days. Ignoring a CDR notice results in the direct suspension and eventual termination of your disability benefits.
3. SSI Redetermination Notice
Supplemental Security Income is a needs-based program designed for seniors and disabled individuals with limited financial resources. A redetermination letter announces a mandatory review of your non-medical financial eligibility.
These reviews occur every one to six years depending on how often your income or living arrangements change. The agency evaluates your bank balances, household expenses, and other financial support.
Current program rules enforce strict asset limits of $2,000 for individuals and $3,000 for married couples. Exceeding these resource thresholds disqualifies you from receiving further SSI payments.
Redetermination notices enforce a strict 30-day response window to provide bank statements, pay stubs, and rent receipts. You may also need to complete a brief telephone or in-person interview.
Failing to respond in time halts your monthly cash payments almost immediately. Even worse, losing your SSI eligibility often terminates your state Medicaid coverage automatically.
4. Notice of Proposed Benefit Reduction or Termination
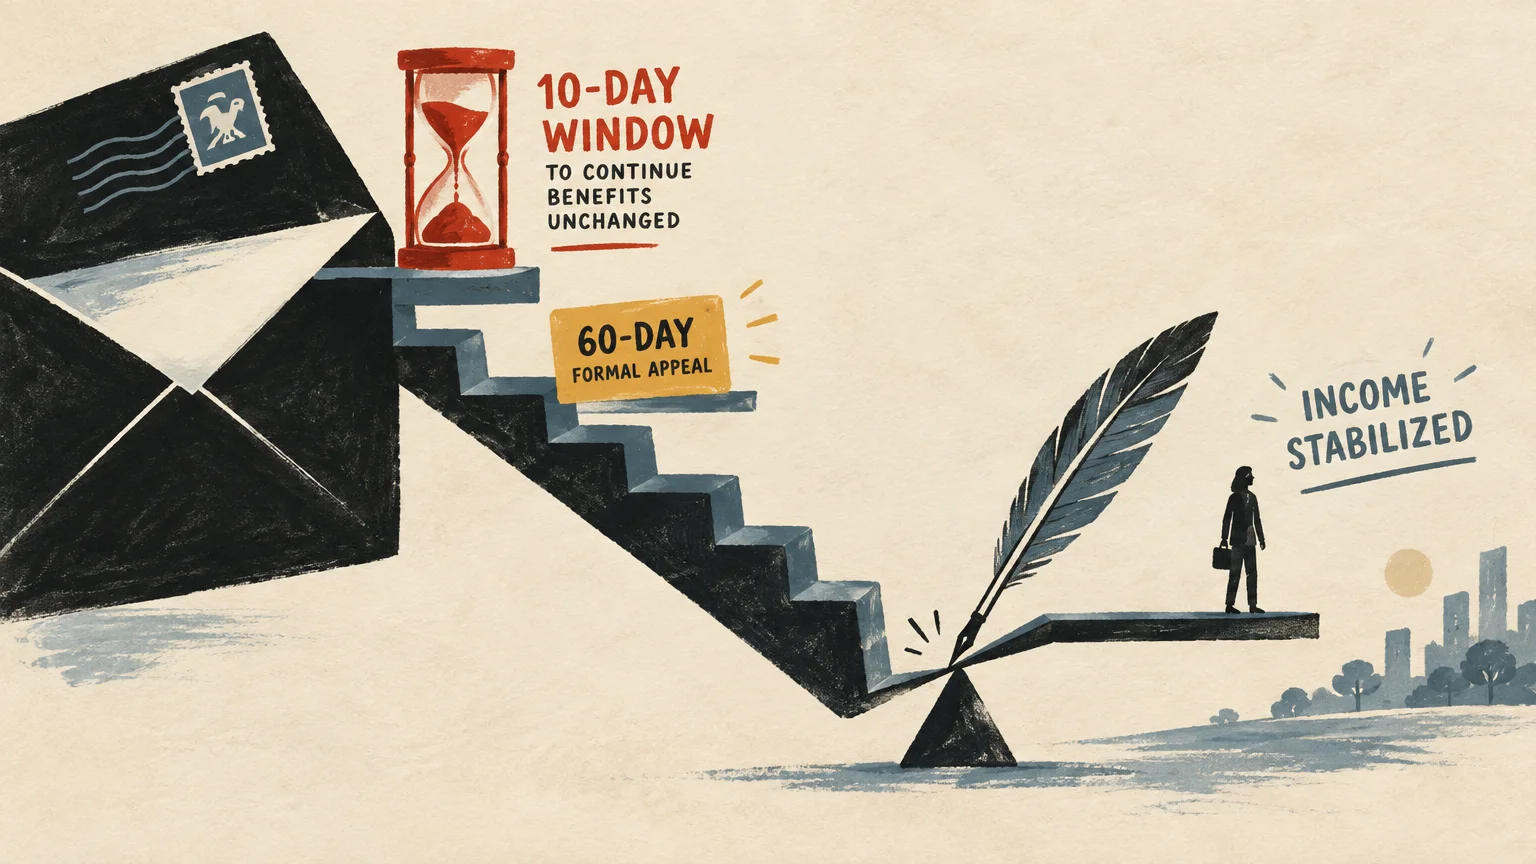
A Notice of Proposed Benefit Reduction or Termination arrives when the government determines you are no longer eligible for your current payment amount. This adverse action notice gives you a critical chance to protect your income.
The most important detail in this letter is the strict 10-day response window for payment continuation. Submitting your appeal within 10 days activates an essential protection called Aid Paid Pending.
Aid Paid Pending ensures that your regular monthly checks continue uninterrupted while your formal appeal is evaluated. If you miss this 10-day cutoff, your checks stop or drop immediately during the review process.
You still retain the standard 60-day window to file Form SSA-561 for reconsideration. However, filing after the 10-day mark means you must endure months of financial hardship without monthly income while waiting for a verdict.
5. Annual Cost-of-Living Adjustment (COLA) Notice
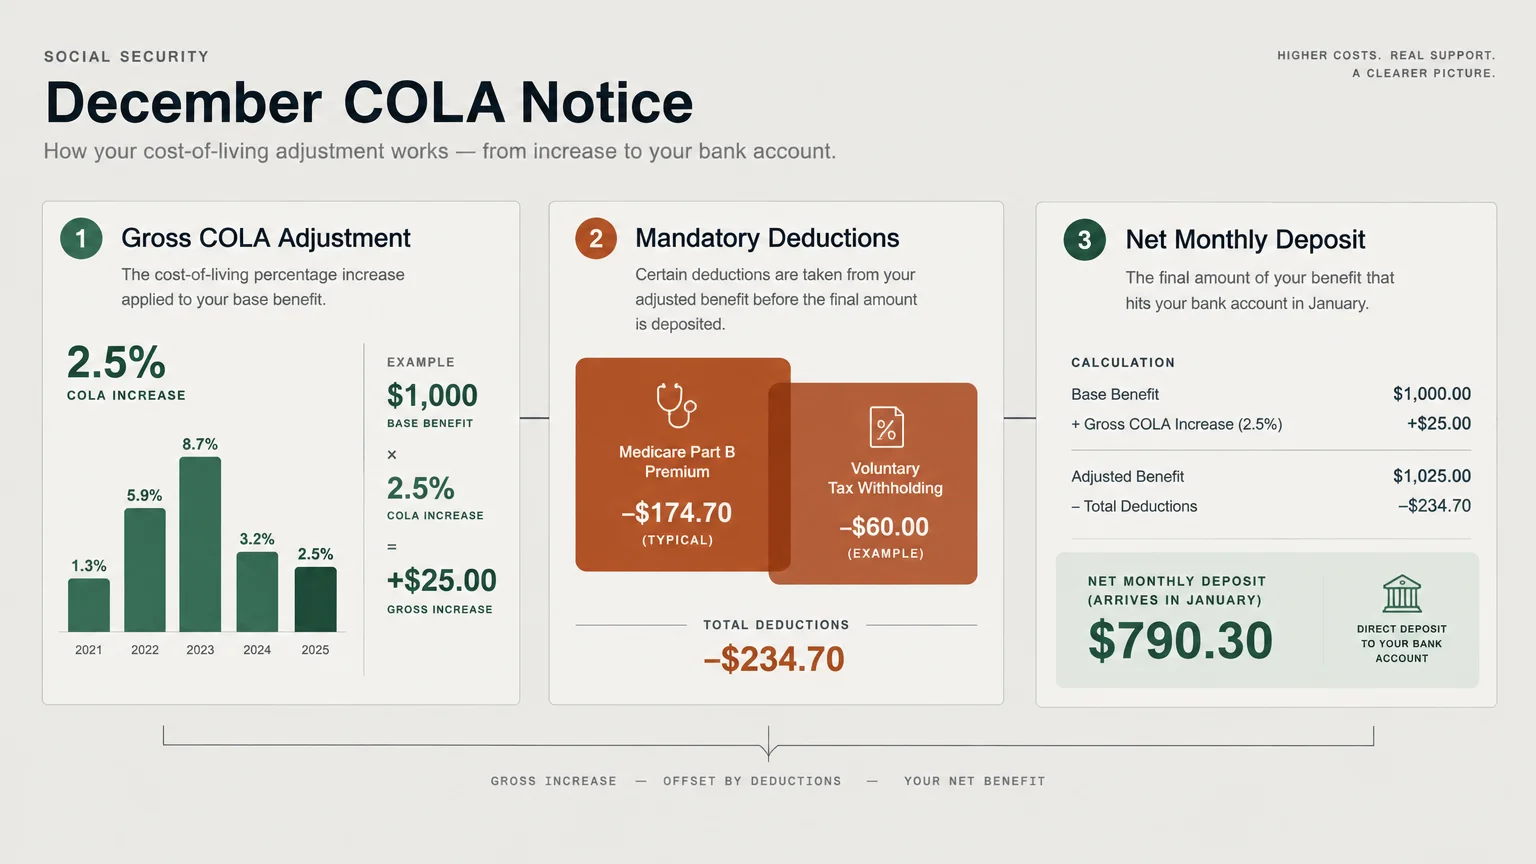
Every December, the Social Security Administration mails an annual Cost-of-Living Adjustment notice to all current beneficiaries. You can also view this notification electronically inside your personal account starting in late November.
Many seniors treat this annual letter as routine junk mail and toss it into the recycling bin. That is a dangerous mistake because this notice outlines your exact cash flow for the entire upcoming year.
The COLA notice details your gross monthly increase alongside mandatory deductions for Medicare Part B standard premiums. You can review official premium guidelines at Medicare.gov.
High-income retirees also see deductions for the Income-Related Monthly Adjustment Amount (IRMAA) listed on this document. Comparing your gross increase against these rising healthcare deductions helps you calculate your true net monthly payout.
Examining this letter immediately allows you to adjust your household budget before January checks arrive. It also helps you spot Medicare enrollment errors or unauthorized deductions before they drain your bank account.
6. Earnings Record Discrepancy Notice
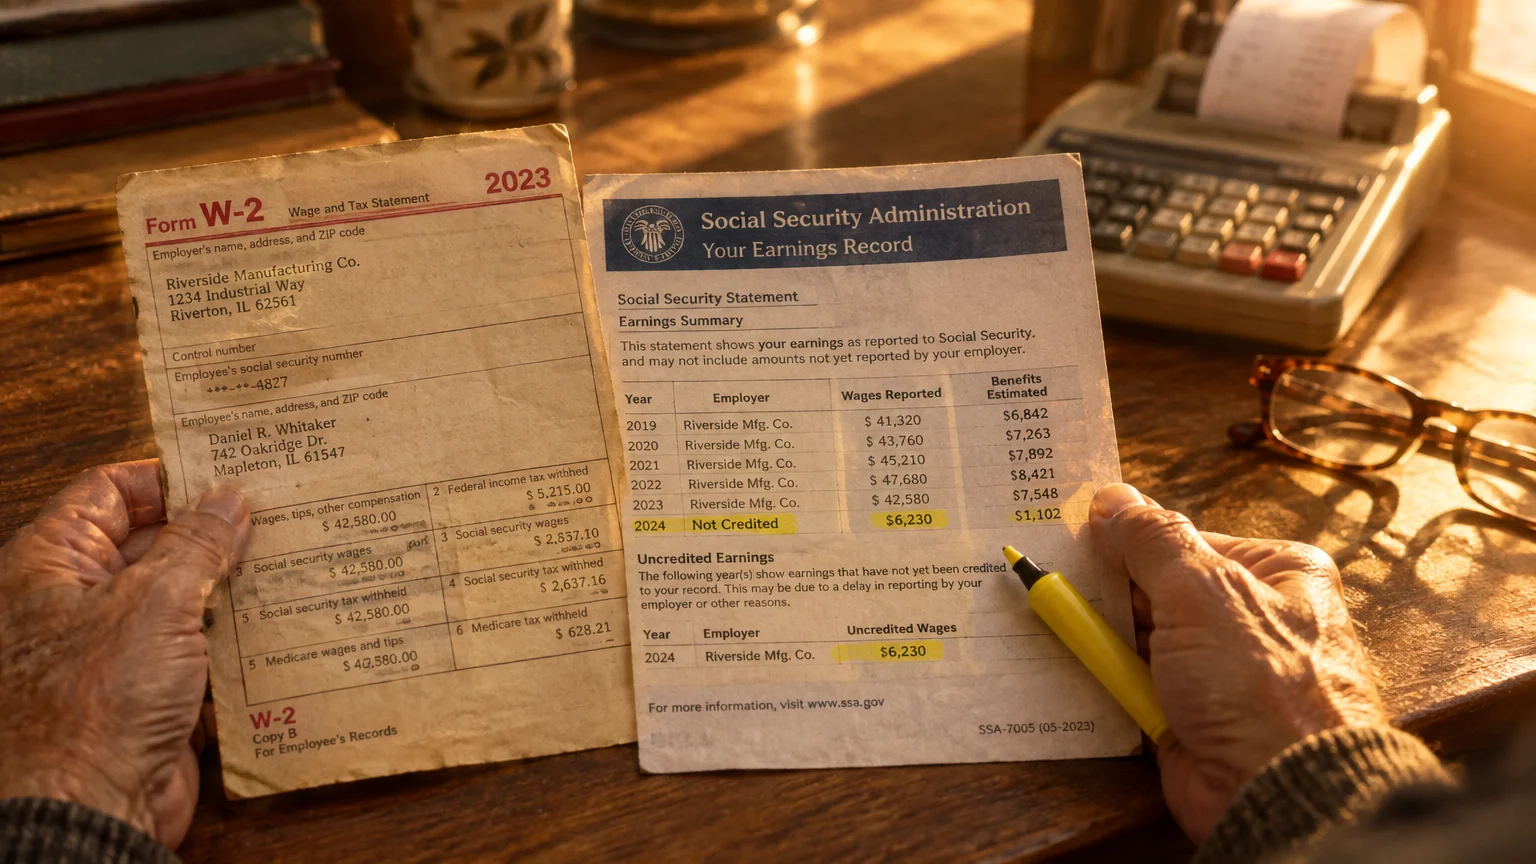
Your future or current retirement benefits depend directly on your lifetime earnings record. When the government spots a mismatch between your reported taxes and agency records, they mail an earnings discrepancy notice.
These discrepancies often happen when an employer mistypes your Social Security number or fails to report your W-2 wages accurately. Self-employed seniors can also face reporting mismatches with the Internal Revenue Service.
Federal law under 42 U.S.C. § 405(c)(1) sets a strict statutory deadline for wage corrections. You have exactly 3 years, 3 months, and 15 days following the close of the taxable year to correct your earnings record.
Once this statutory window closes, correcting your official earnings history becomes nearly impossible without exceptional documentary evidence. Missing wage credits permanently lowers your monthly retirement payout for the rest of your life.
7. Representative Payee Accounting Report (Form SSA-623)
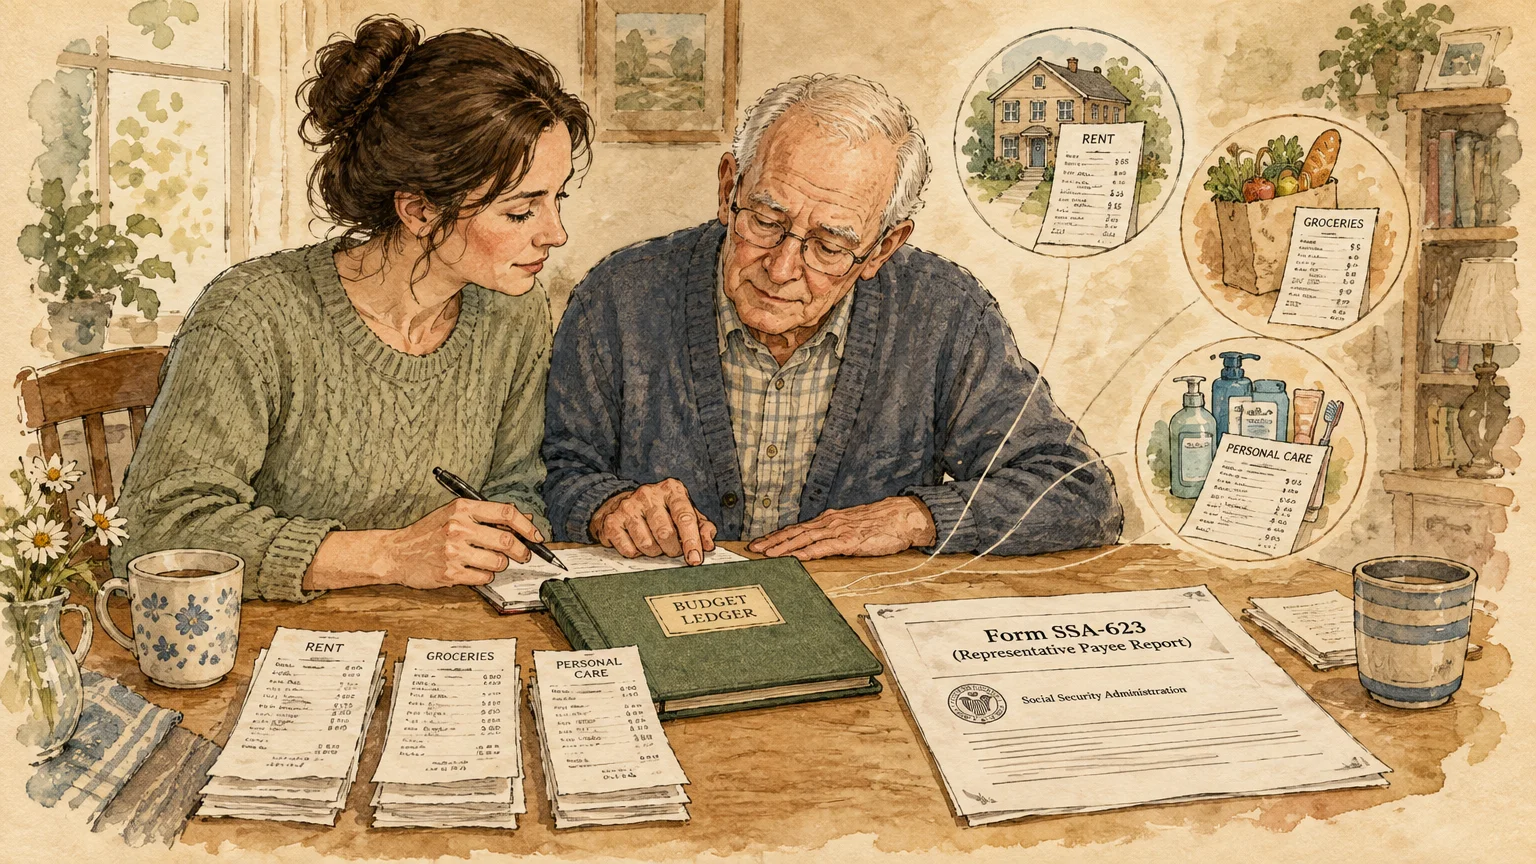
When a senior can no longer manage their own financial affairs, the agency appoints a trusted representative payee. Representative payees receive an annual accounting notice known as Form SSA-623 or Form SSA-6230.
This report requires the payee to document exactly how benefits were spent on housing, food, clothing, and medical care. The agency uses this information to prevent financial elder abuse and neglect.
Under the Strengthening Protections for Social Security Beneficiaries Act, spouses and custodial parents living in the same household are exempt from this annual filing. However, all other appointed payees must complete and submit the paperwork.
Ignoring this annual report triggers an immediate administrative investigation. The agency can freeze benefit distributions, remove you as the designated payee, and initiate a full financial audit of past benefit expenditures.
“A big part of financial freedom is having your heart and mind free from worry about the what-ifs of life.” — Suze Orman, Personal Finance Author
Key Deadlines at a Glance
Tracking response windows prevents unnecessary benefit reductions and administrative freezes. The table below outlines the critical timelines and actions required for each notice.
| Social Security Notice | Response Deadline | Primary Action or Form | Consequence of Inaction |
|---|---|---|---|
| Notice of Overpayment | 30 days to halt withholding; 60 days to appeal | Form SSA-561 (Appeal) or Form SSA-632-BK (Waiver) | Automatic 50% check garnishment (10% for SSI) |
| Continuing Disability Review | Usually 30 days | Form SSA-455 or Form SSA-454-BK | Immediate suspension of disability payments |
| SSI Redetermination | 30 days | Submit income and asset records | Termination of SSI benefits and state Medicaid |
| Proposed Benefit Reduction | 10 days for Aid Paid Pending; 60 days to appeal | Form SSA-561 requesting payment continuation | Loss of monthly benefit checks during the appeal |
| COLA Notice | Review before January payment | Verify Medicare Part B and IRMAA deductions | Budget shortfalls and undetected payroll errors |
| Earnings Discrepancy | 3 years, 3 months, 15 days from tax year | Submit W-2 forms or tax return transcripts | Permanently lower monthly retirement benefits |
| Representative Payee Report | 30 to 60 days as listed | Form SSA-623 or online accounting portal | Revocation of payee status and benefit freezes |
Common Mistakes to Avoid With Social Security Mail
Handling official government correspondence can feel overwhelming, especially when unexpected deadlines loom. Seniors frequently make several critical missteps when receiving official agency mail.
- Confusing an Appeal with a Waiver: An appeal disputes whether an overpayment actually occurred, while a waiver requests debt cancellation because repayment causes severe financial hardship.
- Missing the 10-Day Window for Aid Paid Pending: Waiting past the 10-day cutoff forfeits your legal right to receive benefit checks while your appeal is evaluated.
- Discarding Mail Out of Scam Fears: Tossing legitimate correspondence because it looks intimidating allows automatic collection penalties to take effect.
- Mailing Documents Without Tracking: Submitting paperwork via regular mail risks lost files, leaving you without legal proof of meeting a strict deadline.
If you believe the agency made an error, file Form SSA-561 for reconsideration. If the balance is accurate but you cannot afford repayment, file Form SSA-632-BK for relief.
Always photocopy every page before submitting paperwork to your local office. Send your response via Certified Mail with Return Receipt Requested to prove you met the filing cutoff.
“You cannot make smart financial decisions without accurate, timely information about your income.” — Jean Chatzky, Financial Journalist and Author
How to Verify if a Social Security Letter Is Authentic
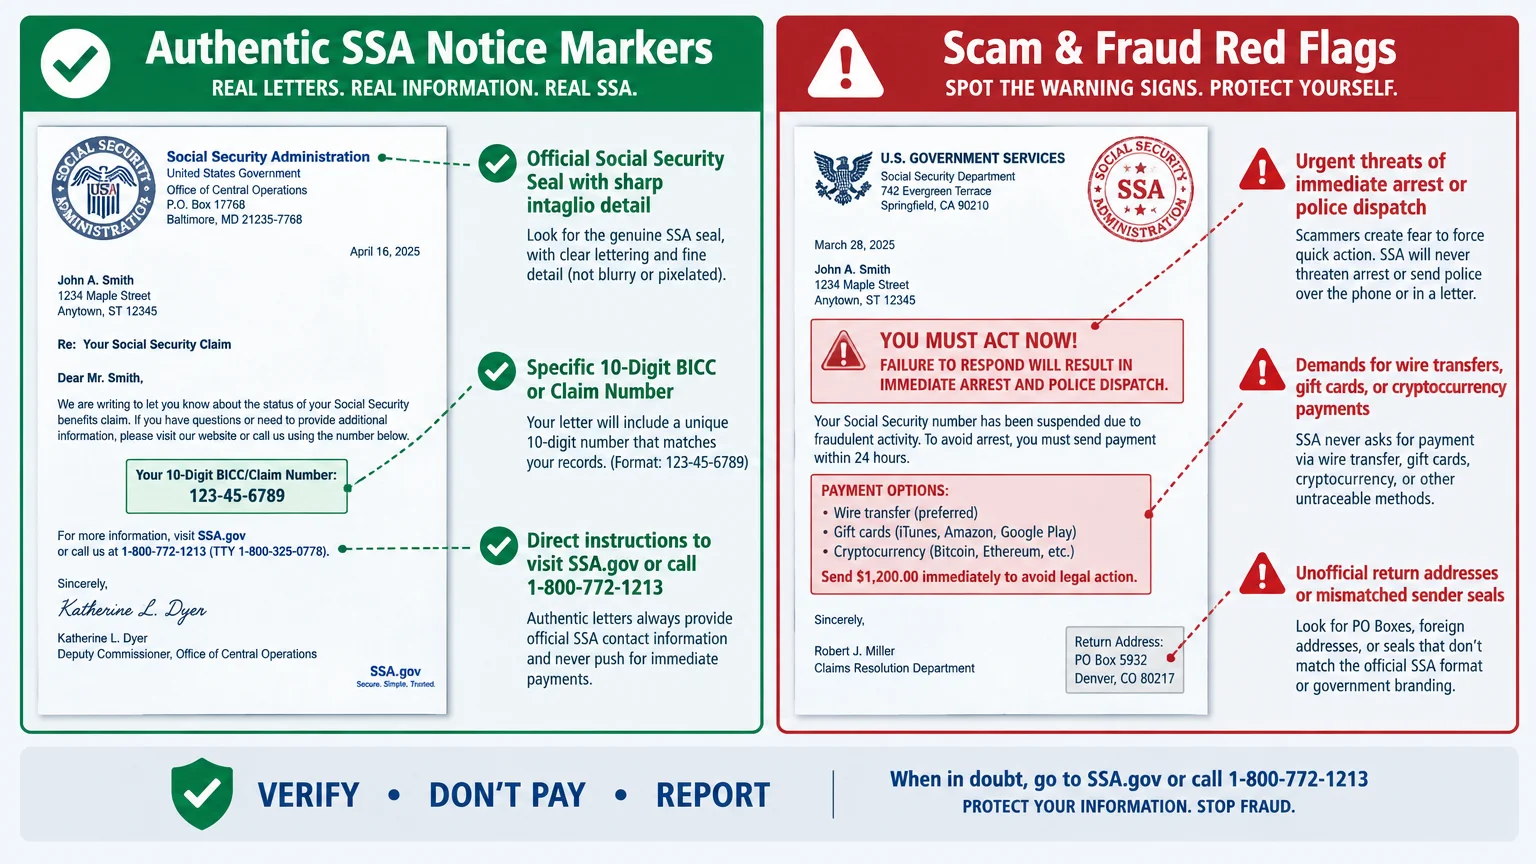
Scammers frequently impersonate government agencies to steal personal information and banking details. The Consumer Financial Protection Bureau warns seniors to watch for aggressive threats and demands for immediate payment.
Legitimate agency notices never demand payments via wire transfers, prepaid debit cards, cryptocurrency, or gift cards. They will also never threaten you with immediate arrest by local police.
You can verify any questionable mailing by logging into your personal online portal. The agency posts copies of official letters directly to your secure Message Center.
If a mailed notice does not appear in your online account, call the agency directly at 1-800-772-1213. Never call the phone number printed on an unverified or suspicious letter.
When to Seek Professional Guidance
Navigating complex Social Security notices sometimes requires professional assistance beyond standard customer service lines. In several specific situations, consulting an expert protects your financial future.
Consider hiring an attorney or certified representative if you face an administrative law judge hearing for disability benefits. Disability advocates work on a regulated contingency fee basis and understand complex medical regulations.
Consult a licensed fee-only financial planner if you receive an unexpected overpayment demand exceeding $10,000. An advisor can help structure repayment plans without triggering severe tax consequences.
Contact a local Legal Aid organization if you face an SSI redetermination that threatens your Medicaid eligibility. Low-income seniors can often access free legal defense for essential public benefits.
Frequently Asked Questions
What should I do if I move and miss an important letter?
Update your mailing address immediately through your online Social Security account or by calling customer service. If you missed a deadline due to a move, file your response immediately along with a written statement explaining good cause for the delay.
Can the SSA recover an overpayment if the mistake was entirely their fault?
Yes, federal law requires the agency to recover overpaid funds even if an agency worker made the error. However, being free of fault qualifies you to request an overpayment waiver using Form SSA-632-BK.
Does an overpayment waiver request have a strict filing deadline?
No, an overpayment waiver carries no official expiration deadline. You can submit Form SSA-632-BK at any point, even years after the agency began recouping the overpaid funds.
How long do I have to appeal an unfavorable decision?
You have 60 days from the date you receive the notice to submit Form SSA-561 for reconsideration. The agency presumes you received the notice five days after mailing, providing an effective 65-day deadline.
Taking Immediate Action to Protect Your Benefits
Never leave official government envelopes unopened on your kitchen counter. Opening mail promptly gives you time to understand your rights, gather documentation, and meet crucial deadlines.
Mark all deadlines on your calendar, keep photocopies of every response, and use certified mail for all correspondence. Taking control of your paperwork today safeguards your monthly retirement security tomorrow.
The information in this guide is meant for educational purposes. Your specific circumstances—including income, benefits, tax situation, and health needs—may require different approaches; when in doubt, consult a licensed financial advisor or tax professional.
Last updated: February 2026. Benefit amounts, tax rules, and program details change annually—verify current figures with official government sources.

Leave a Reply