
State taxes can quickly shrink your hard-earned pension checks. Fortunately, lawmakers across the country are cutting or eliminating these taxes to keep retirees from moving away.
Several states have recently passed major reforms to exempt your retirement annuities and defined-benefit distributions. Others are actively debating bills that could put thousands of dollars back into your budget.
Understanding these legislative shifts helps you protect your retirement cash flow. Here is a look at ten states reconsidering pension income taxes and what these changes mean for you.
Why States Are Overhauling Pension Taxes
State governments increasingly recognize that aggressive retirement taxes drive wealth out of their local economies. When retirees relocate, states lose valuable sales taxes, property taxes, and community leadership.
To stem this outbound migration, governors and legislators are racing to make their tax codes friendlier to seniors. These reforms often target defined-benefit pensions, 401(k) plans, and public service annuities.
Staying informed about your state’s tax policy ensures you keep more of your hard-earned benefits. You can track federal retirement baselines through the Internal Revenue Service (IRS) while monitoring local legislative changes.
“Taxes are often the single largest expense you will face in retirement, yet most people fail to plan for them until it is too late.” — Ed Slott, CPA and Retirement Distribution Expert
1. Michigan: Phasing Out the Controversial Retirement Tax
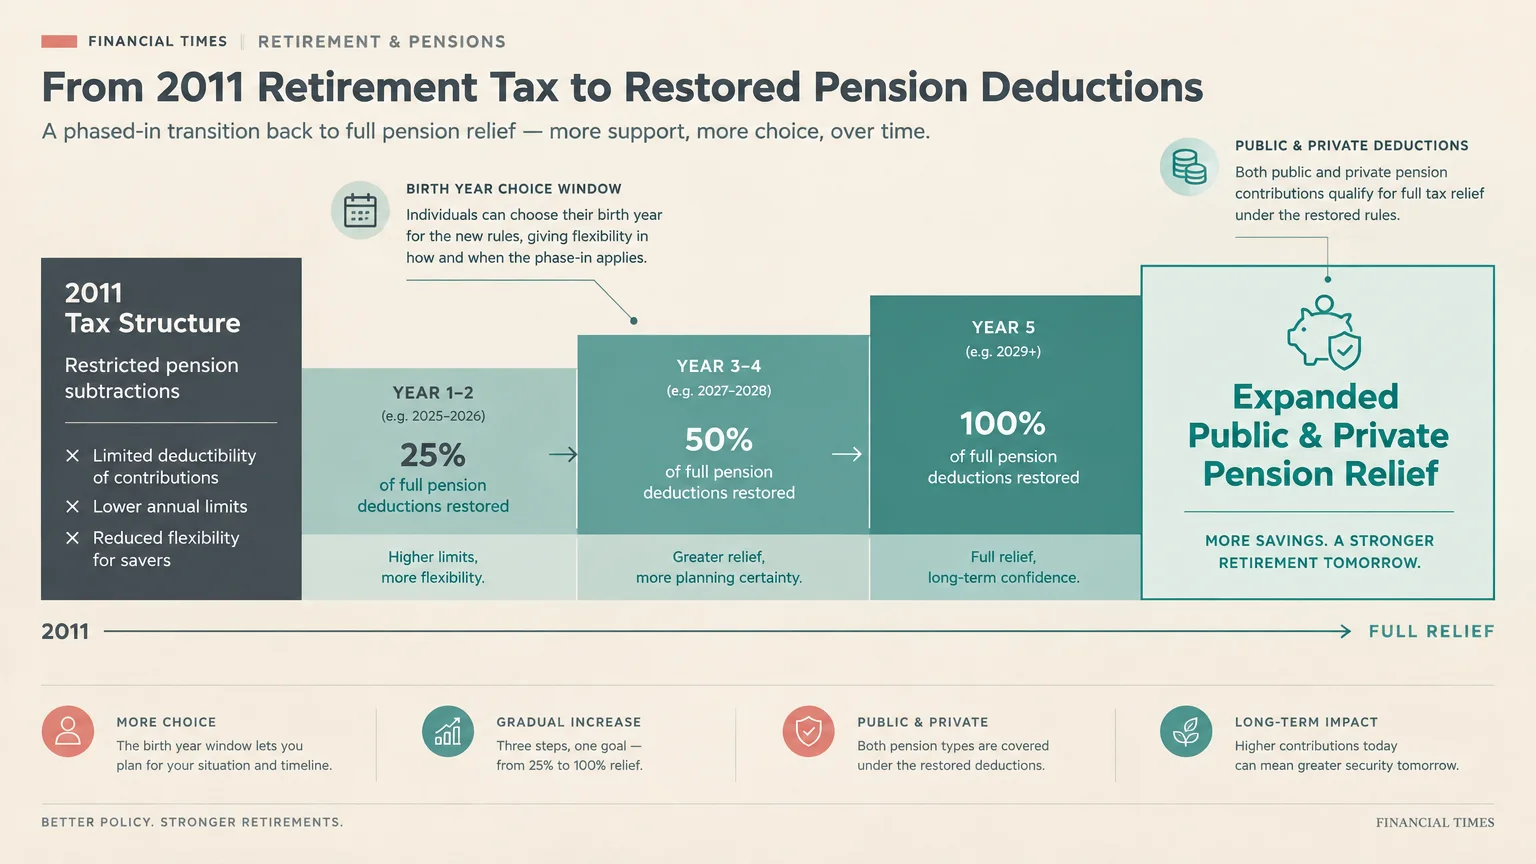
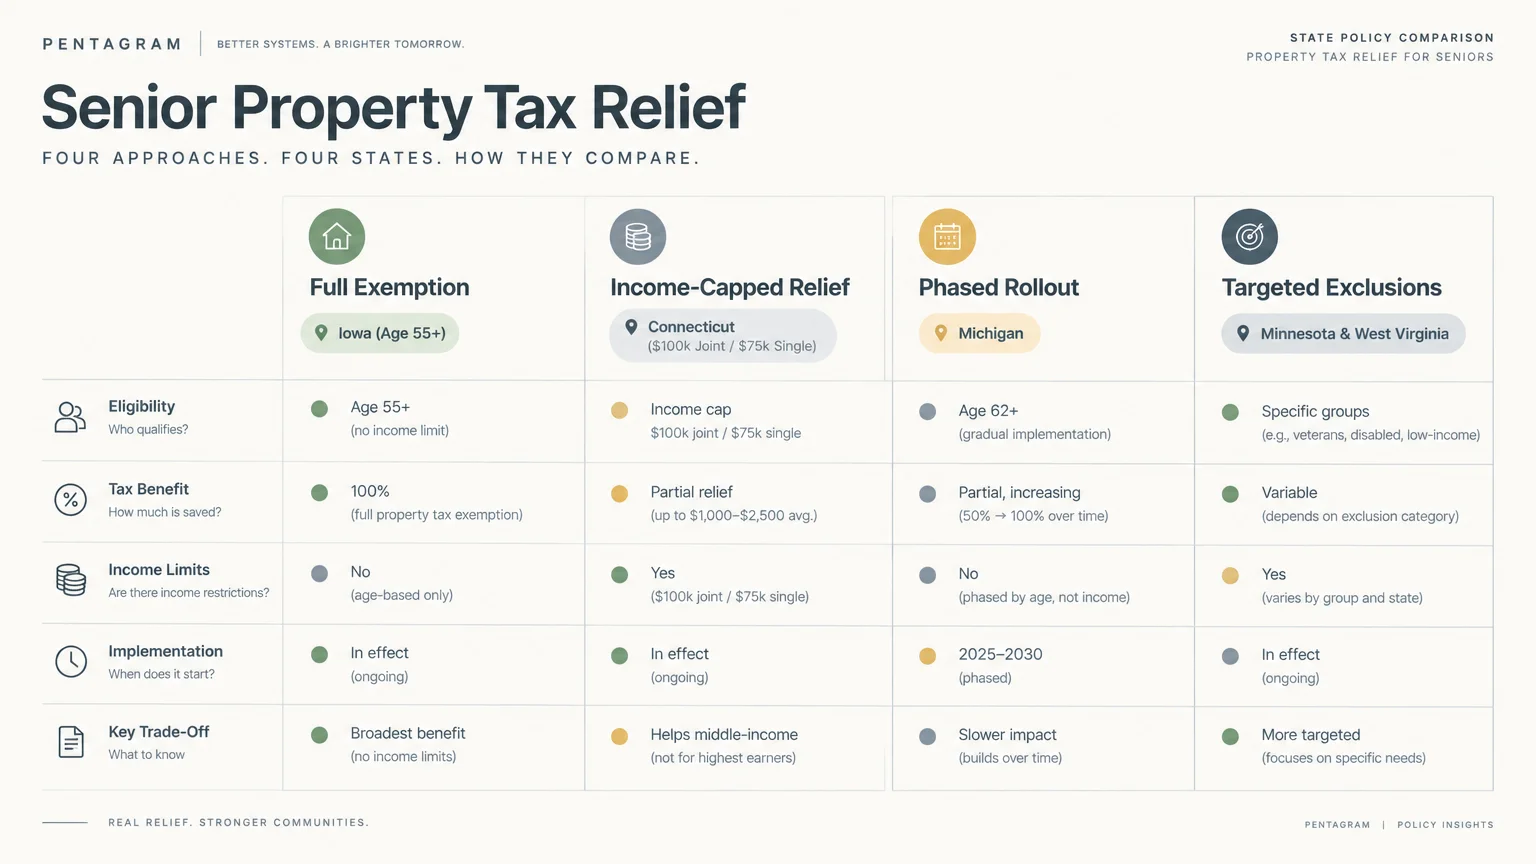
Michigan enacted sweeping legislation to roll back its 2011 retirement tax. This change restores broad deductions for both public and private pensions over a multi-year phase-in period.
Qualified taxpayers can choose between older, generous exemption systems or newer expanded subtractions. This flexibility gives you the ability to claim the deduction that yields the lowest tax bill.
The phase-in expands relief substantially each filing season. Check with the Michigan Department of Treasury to confirm your exact birth year qualifications.
2. Connecticut: Expanding Income Thresholds for Seniors
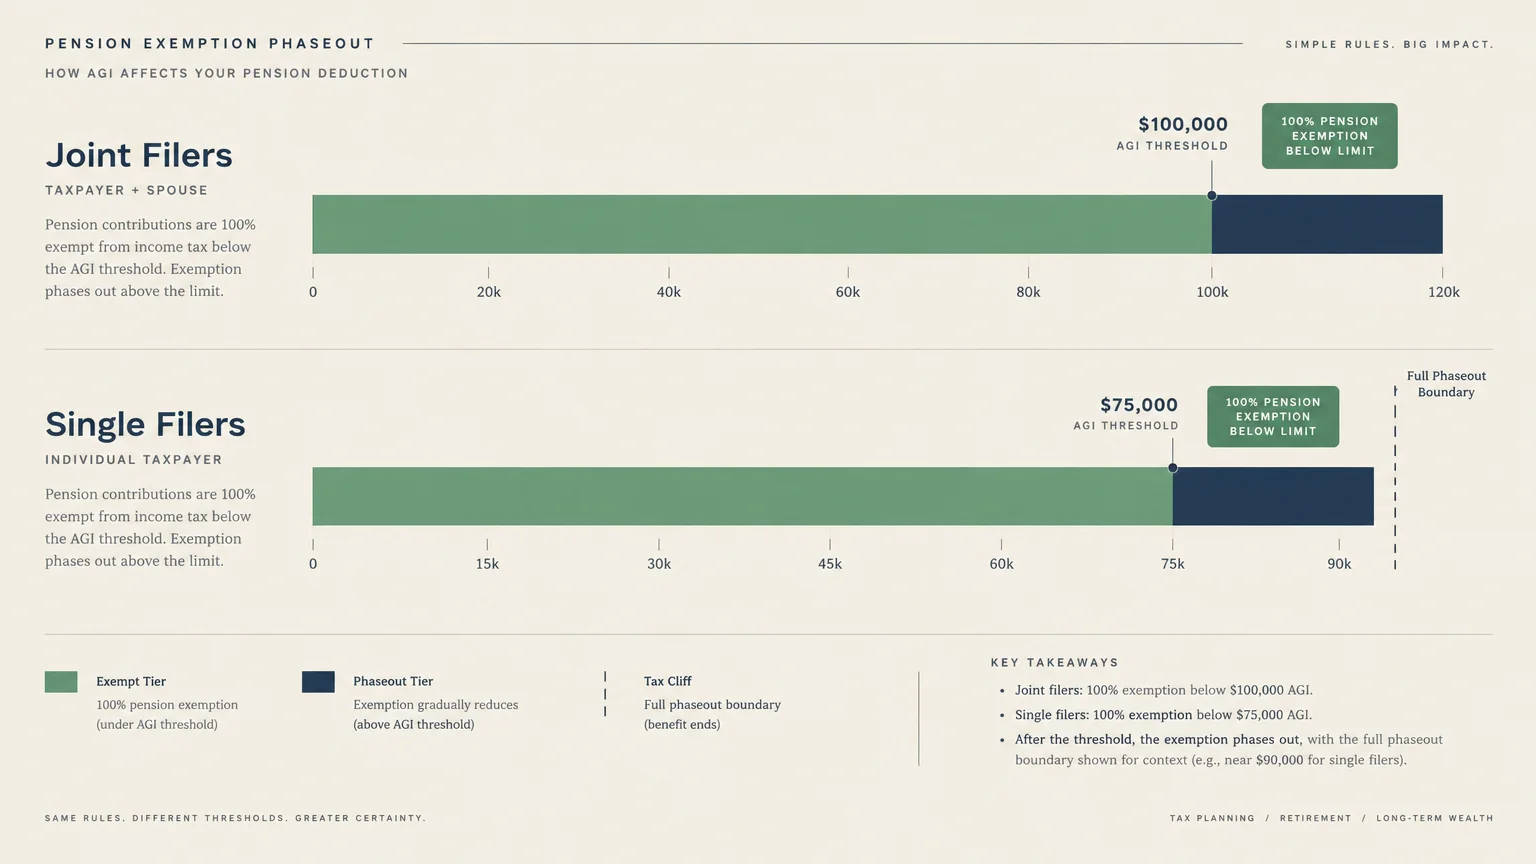
Connecticut lawmakers have expanded exemptions on qualifying pension and annuity distributions. Under recent statutory updates, qualifying joint filers earning under $100,000 deduct 100% of their pension income.
Single filers with adjusted gross income under $75,000 also qualify for this complete state tax exemption. Lawmakers continue debating whether to lift these income caps entirely to help more middle-class households.
If your earnings sit near these limits, careful financial planning is essential. A small spike in income could trigger unexpected state taxation on your entire pension.
3. Iowa: Complete Elimination of Retirement Income Taxes
Iowa transformed its retirement landscape by fully exempting pension income, 401(k) distributions, and IRA withdrawals. This statutory exemption applies to all residents aged 55 and older.
The state previously taxed retirement income at high marginal rates. Removing this tax entirely positions Iowa as one of the most competitive Midwestern destinations for seniors.
You do not need to meet complex income limits to claim this relief. If you meet the age criteria, your pension distributions are entirely exempt from Iowa state income tax.
4. Minnesota: Reassessing Exclusions to Retain Retirees
Minnesota has long held a reputation for taxing most forms of retirement income, including public pensions. However, recent sessions expanded targeted tax subtractions for seniors facing rising living costs.
Legislative leaders continue pushing bipartisan proposals to fully exempt all public and private pensions. Proponents argue this reform is critical to prevent older residents from moving south.
While full elimination remains under debate, existing exemptions have broadened significantly. Review current state brackets each season to determine your eligible deduction amount.
5. West Virginia: Accelerating Relief for Fixed-Income Seniors
West Virginia completed a phased elimination of state income taxes on Social Security benefits. Building on this momentum, state legislators have introduced proposals to broaden exemptions for public employee pensions.
These policy shifts aim to make the Mountain State an affordable haven for regional retirees. Targeted subtractions already protect many police, firefighter, and military retirement annuities.
Broader bills under review would extend similar protections to private sector retirees. Check filing guidelines with the West Virginia State Tax Division as new provisions clear the legislature.
6. Rhode Island: Raising the Bar on Pension Deductions
Rhode Island continues adjusting its retirement tax system to protect middle-income seniors. State law provides income-limited deductions for qualifying public and private pensions alongside military retirement exemptions.
Advocates are actively lobbying the General Assembly to raise these income thresholds. Higher limits would prevent annual cost-of-living adjustments from pushing retirees into taxable territory.
You can verify current income cutoffs on the Rhode Island Division of Taxation website. If your income falls below the statutory threshold, your qualifying pension payments remain tax-free.
7. Kansas: Transitioning Toward Senior Tax Relief
Kansas enacted legislation eliminating state taxes on Social Security earnings. Following that victory, lawmakers introduced measures to expand exclusions for private retirement plans and local pensions.
While state-level public pensions already enjoy exemptions, private sector pensions still face regular income taxes. Pending legislation seeks to create tax parity between all pension recipients across the state.
Leveling the playing field would save private retirees thousands of dollars annually. Track pending bills in Topeka if you receive a private company pension.
8. Vermont: Broadening Exemptions for Middle Earners
Vermont historically taxed most retirement income at standard state rates. In recent legislative sessions, lawmakers introduced phased exemptions for civil service pensions alongside expanded Social Security tax credits.
Current legislative debates focus on raising adjusted gross income thresholds so more retirees qualify. Advocates emphasize that retaining older residents strengthens the local volunteer base and economy.
Check the Vermont Department of Taxes before filing to see if you qualify. Marginal earners can often use these credits to eliminate their state liability.
9. Maryland: Bipartisan Pressure to Slash Retirement Taxes
Maryland offers a substantial pension exclusion for older residents, but qualification rules remain intricate. Lawmakers frequently introduce measures like the “Keep Our Seniors in Maryland Act” to simplify these rules.
The state adjusts its maximum pension exclusion annually based on statutory calculations. Qualifying individuals aged 65 and older can deduct significant portions of their defined-benefit payments.
Senior advocacy groups such as AARP continue lobbying Annapolis for broader, universal pension subtractions. Check state revenue bulletins to view this year’s maximum exclusion limit.
10. Nebraska: Following Social Security Relief with Pension Overhauls
Nebraska successfully phased out state income taxes on Social Security benefits ahead of schedule. Encouraged by this milestone, legislative leaders are debating expanded relief for private and public pension annuities.
These proposals aim to keep older Nebraskans from migrating to states with zero income tax. Several proposals seek to match the tax exemptions already granted to military retirees.
As state revenue allows, lawmakers plan to broaden general retirement exemptions. Keep an eye on legislative floor debates if you collect a pension in Nebraska.
Comparing State Pension Tax Policies at a Glance
Understanding how different states approach pension income helps you plan your retirement residency. The table below summarizes recent legislative trends across these ten states.
| State | Recent Reform Direction | Key Tax Rule to Verify |
|---|---|---|
| Michigan | Phasing out 2011 retirement tax | Check birth year phase-in rules |
| Connecticut | Expanded income exemptions | Monitor adjusted gross income limits |
| Iowa | Fully exempt for age 55+ | Applies automatically to eligible ages |
| Minnesota | Expanding subtractions; debating total relief | Review adjusted gross income phaseouts |
| West Virginia | Phasing out senior taxes; expanding exclusions | Track public employee deduction limits |
| Rhode Island | Adjusting income eligibility caps | Verify annual income threshold limits |
| Kansas | Debating private pension tax parity | Distinguish public from private rules |
| Vermont | Raising income thresholds on exemptions | Confirm current state credit eligibility |
| Maryland | Increasing maximum allowable exclusions | Check annual maximum exclusion dollar cap |
| Nebraska | Debating comprehensive pension exemptions | Follow pending legislative committee bills |
Key Considerations for Managing Your Pension Taxes
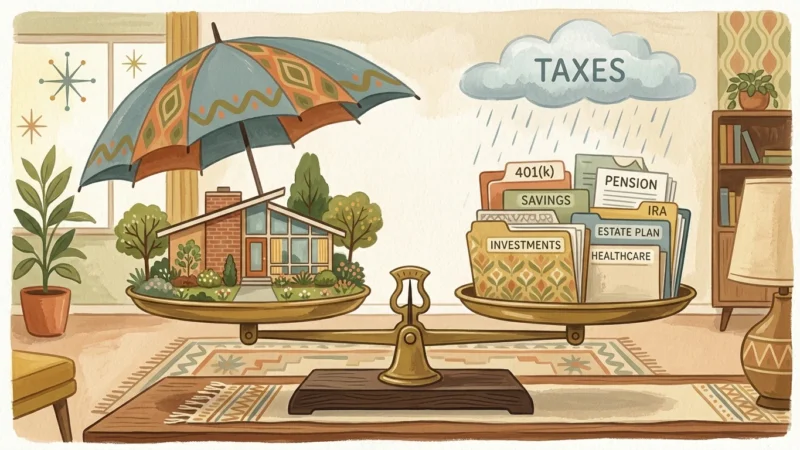
Legislative changes take time to settle into administrative practice. You must evaluate how state updates mesh with federal rules and your total income picture.
- Federal Taxation Remains: State-level exemptions do not change federal income tax obligations on your defined-benefit distributions.
- Withholding Adjustments: When your state lowers taxes on pensions, you may need to submit updated state withholding forms.
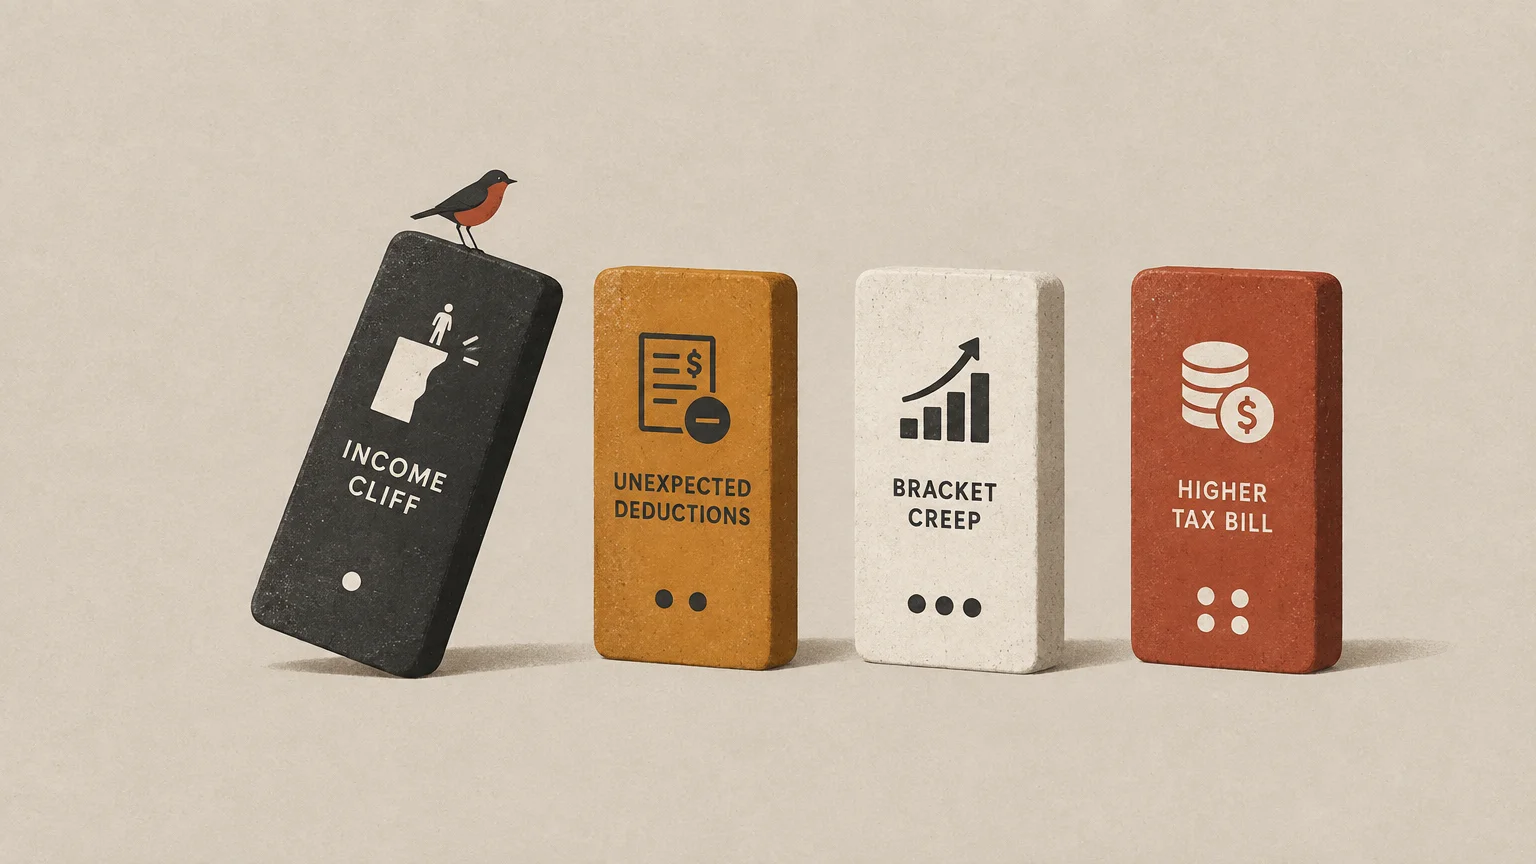
- Income Cliffs: In states with rigid income caps, earning an extra dollar can sometimes make your entire pension taxable.
- Inflation Adjustments: Verify whether your state adjusts pension exemption thresholds automatically for annual inflation.
For official federal benefit verification and withholding rules, visit the Social Security Administration (SSA) alongside your state revenue department.
What Can Go Wrong: 4 Retirement Tax Mistakes
Navigating retirement tax legislation requires attention to detail. Many retirees assume too much and face unexpected penalties or surprise tax bills.
1. Assuming Federal Rules Match State Laws
Just because your state exempts pension income does not mean the IRS does the same. You must still account for federal tax withholding on every distribution.
2. Overlooking Sudden Income Cliffs
Several states terminate pension exclusions completely once your income exceeds a set dollar cap. Crossing that line by a nominal amount can cause a significant tax hike.
3. Failing to Update State Withholding Forms
Pension plan administrators do not always alter withholding amounts automatically following legislative changes. You must submit revised withholding paperwork to reflect updated tax policies.
4. Misjudging Domicile and Residency Rules
Buying a vacation home does not immediately change your legal state of residency. States audit departure dates and property ties aggressively before relinquishing your tax obligations.
When to Consult a Professional
While public tax rules are available online, applying them to your personal life can be complicated. Specific scenarios demand professional review from a Certified Financial Planner (CFP) or CPA.
Consider consulting a professional if you plan to move across state lines during retirement. A tax advisor will verify residency requirements to prevent double-taxation on deferred income.
You should also seek guidance if your income hovers right near a state exemption threshold. Strategic charitable donations or timing retirement distributions can keep you below taxable limits.
Finally, work with an expert if you combine public pensions, private annuities, and military retirement pay. Each income stream may fall under distinct state deduction rules.
Frequently Asked Questions
Do all states tax private pension income?
No, several states have no personal income tax at all, while others specifically exempt retirement income. Many states exempt pension income entirely once you meet age and residency requirements.
Can my former state tax my pension if I move away?
Federal law prohibits states from taxing pension payments earned by individuals who have established permanent residency elsewhere. Your current legal state of domicile governs pension income taxes.
What is the difference between a pension exclusion and a tax credit?
A pension exclusion reduces the total adjusted gross income subject to state taxes. A tax credit, on the other hand, reduces your final calculated tax balance dollar-for-dollar.
Do pension exemptions apply to 401(k) and IRA distributions?
It depends on state statutory language. Some states treat traditional 401(k) and IRA withdrawals the same as pensions, while others limit relief strictly to defined-benefit plans.
Securing Your Retirement Cash Flow
State pension tax laws are evolving rapidly as lawmakers compete to retain active, tax-paying seniors. Following these updates allows you to adjust your withholdings and prevent expensive filing surprises.
Review your state’s latest tax forms every January to confirm newly enacted subtractions. Taking proactive control of your retirement plan ensures your fixed income stretches as far as possible.
This article provides general financial education and information only. Everyone’s financial situation is unique—what works for others may not work for you. For personalized advice tailored to your retirement needs, consider consulting a qualified financial professional such as a CFP or CPA.
Last updated: February 2026. Benefit amounts, tax rules, and program details change annually—verify current figures with official government sources.
Leave a Reply