What Can Go Wrong: 4 Retirement Tax Mistakes
Navigating retirement tax legislation requires attention to detail. Many retirees assume too much and face unexpected penalties or surprise tax bills.
1. Assuming Federal Rules Match State Laws
Just because your state exempts pension income does not mean the IRS does the same. You must still account for federal tax withholding on every distribution.
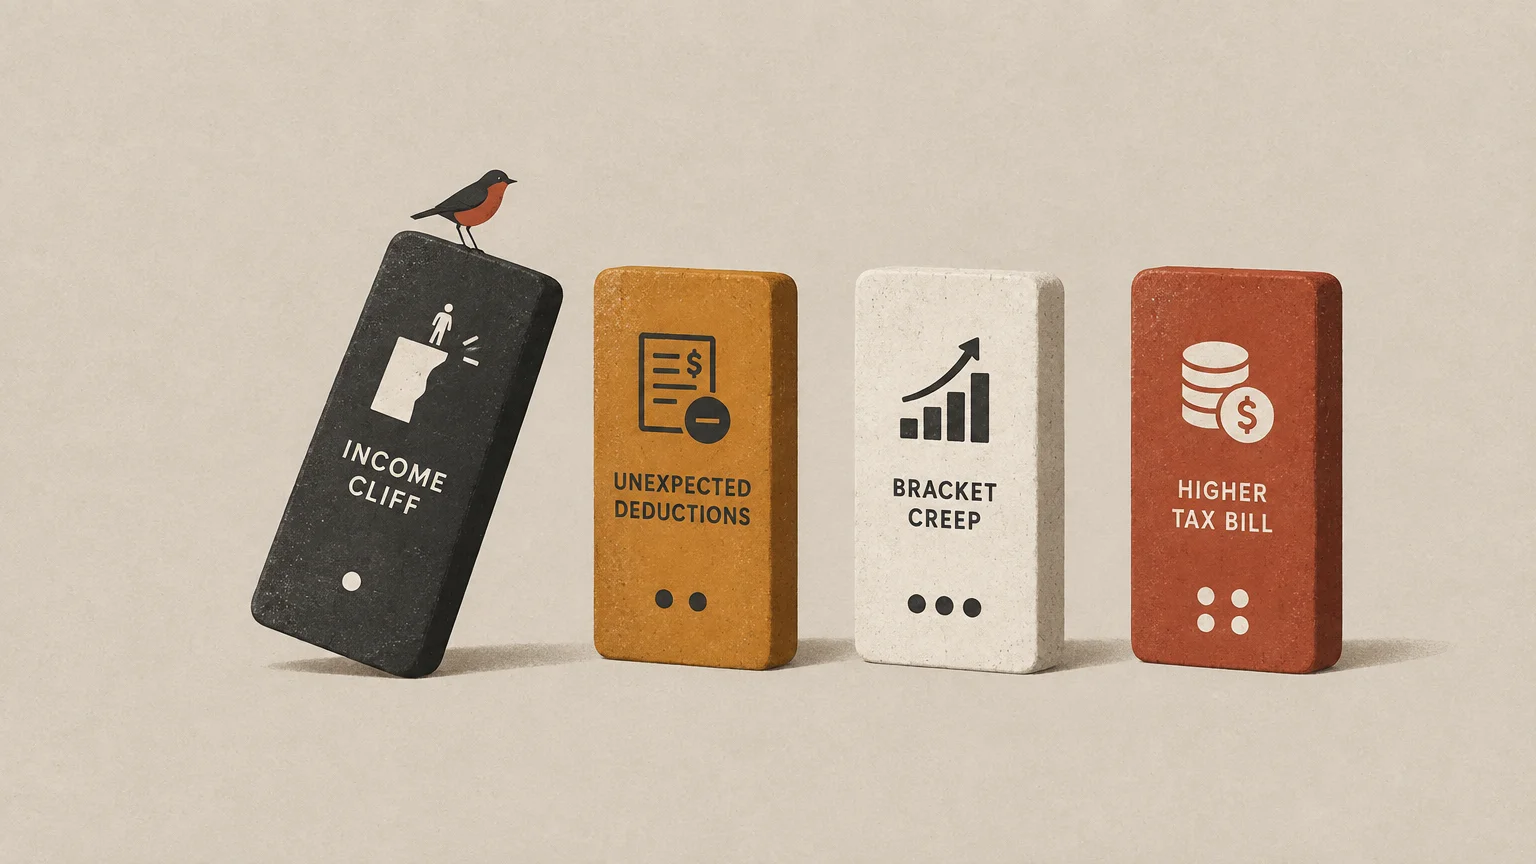
2. Overlooking Sudden Income Cliffs
Several states terminate pension exclusions completely once your income exceeds a set dollar cap. Crossing that line by a nominal amount can cause a significant tax hike.
3. Failing to Update State Withholding Forms
Pension plan administrators do not always alter withholding amounts automatically following legislative changes. You must submit revised withholding paperwork to reflect updated tax policies.
4. Misjudging Domicile and Residency Rules
Buying a vacation home does not immediately change your legal state of residency. States audit departure dates and property ties aggressively before relinquishing your tax obligations.
Leave a Reply