
Finding the perfect coastal village or mountain haven requires balancing scenic charm with your long-term retirement budget. New England offers world-class healthcare, historic architecture, and surprising tax advantages for seniors who choose strategically.
Choosing where to retire in New England often involves balancing state tax exemptions against municipal property tax rates. The right town protects your hard-earned nest egg while keeping you active and deeply engaged.
These eight standout communities deliver exceptional quality of life, dependable medical infrastructure, and welcoming neighborhoods for your next chapter.
The Financial Landscape for New England Retirees
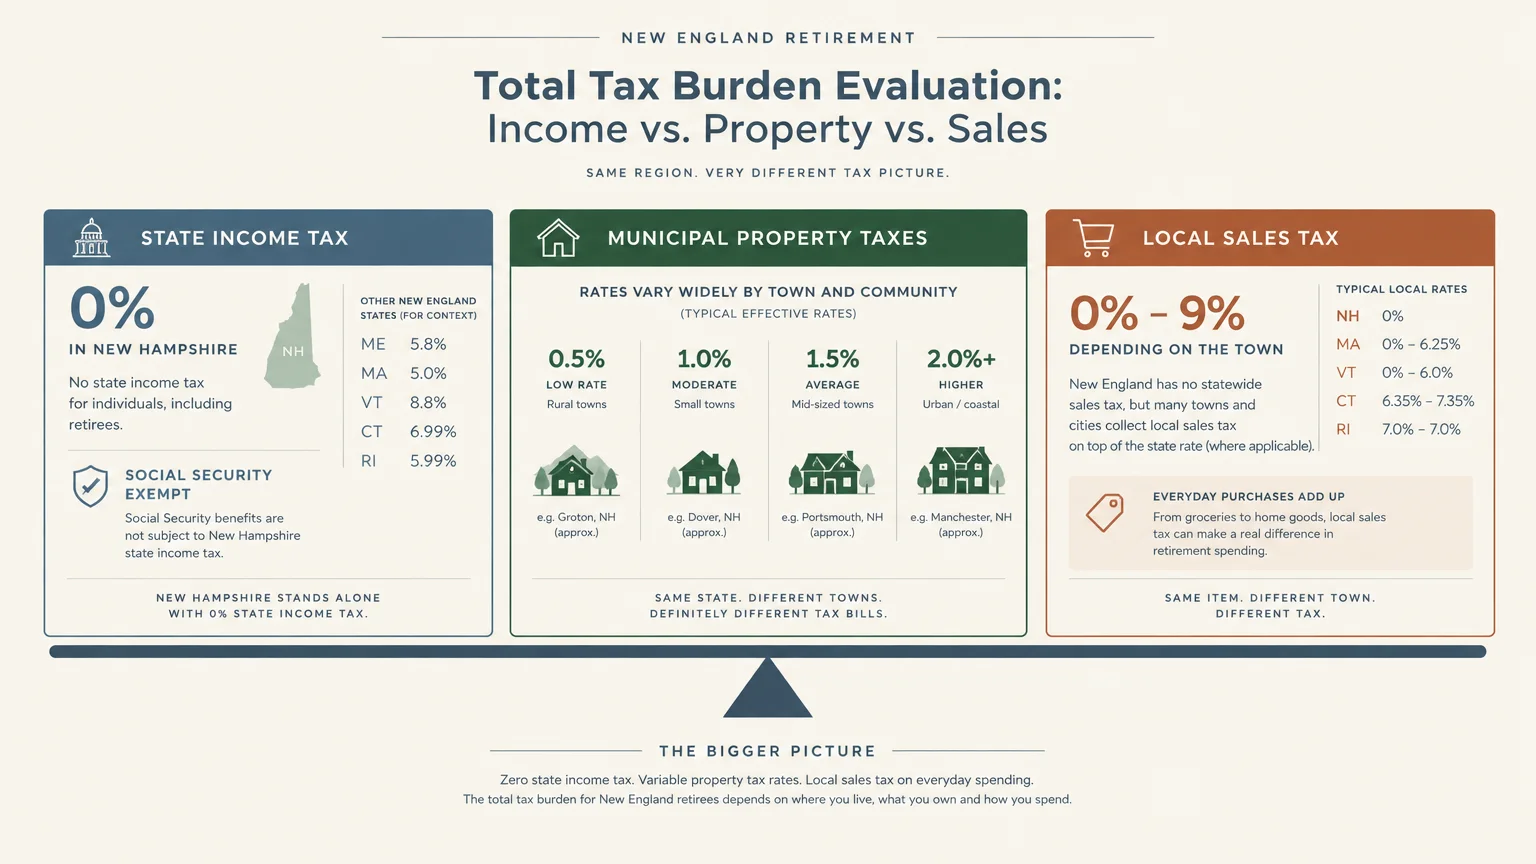
New England has a reputation for high living costs, yet state tax policies vary significantly across individual borders.
While certain states tax retirement distributions, others offer generous exemptions on private pensions, Social Security, and investment earnings.
“The single biggest factor that determines how much of your hard-earned retirement nest egg you actually keep is tax planning.” — Ed Slott, CPA and IRA Expert
According to the Internal Revenue Service (IRS), federal guidelines establish your taxable baseline, but state statutes dictate your final net income.
You must evaluate state income taxes, municipal property levies, and local sales taxes together rather than viewing any single expense in isolation.
8 Best New England Towns for Retirees
1. Portsmouth, New Hampshire
Portsmouth pairs classic eighteenth-century maritime architecture with a vibrant, walkable downtown along the Piscataqua River.
You can browse independent bookstores, dine at historic waterfront taverns, and attend live concerts at The Music Hall.
New Hampshire offers major tax advantages for retirees drawing from investment portfolios. Effective January 1, 2025, New Hampshire repealed its Interest and Dividends Tax, completing its transition to zero state income tax.
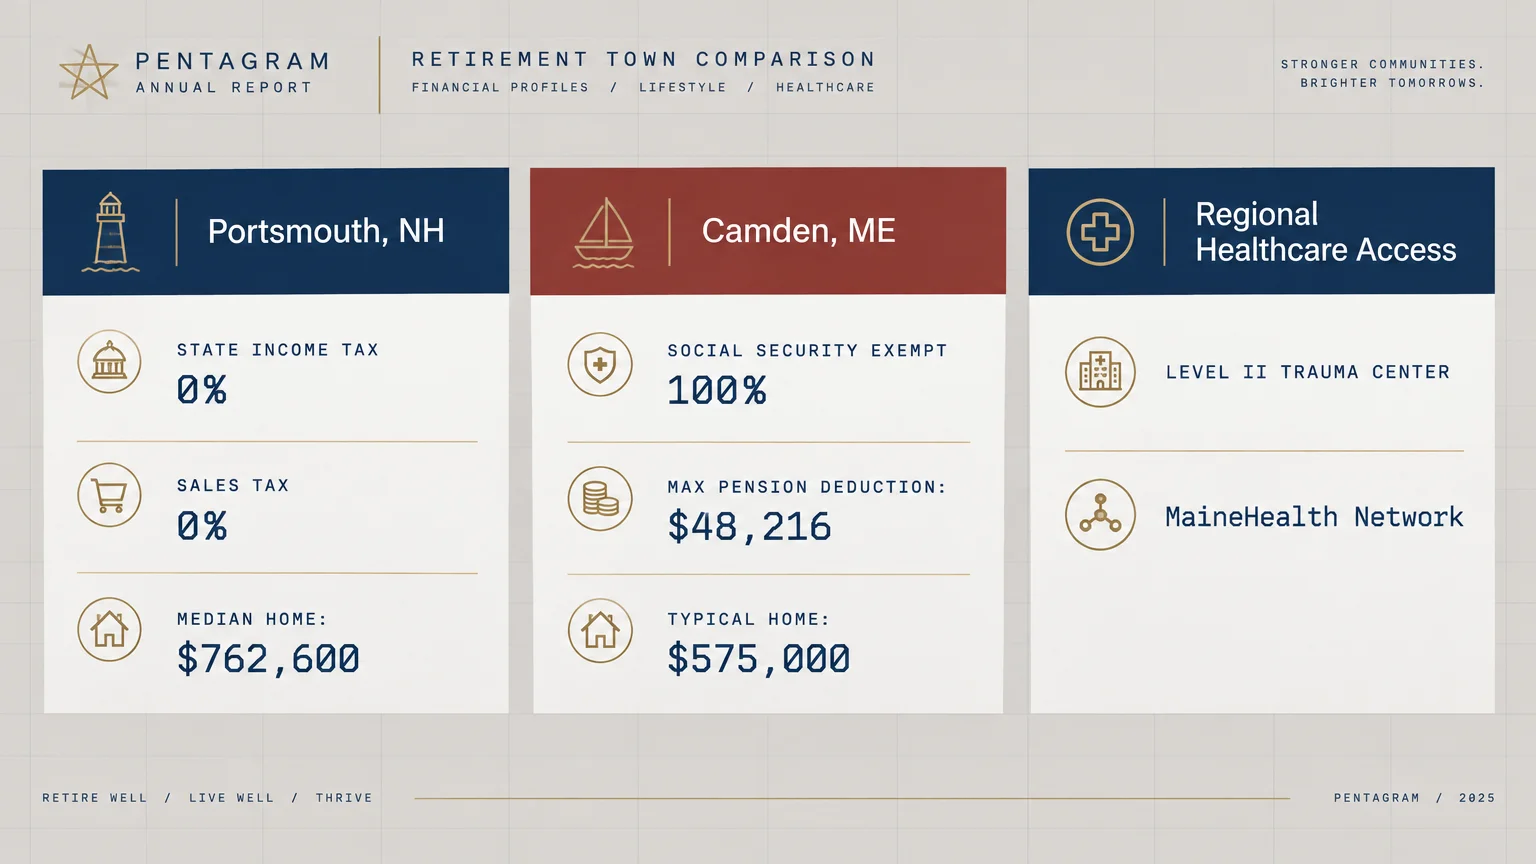
You pay 0% state tax on Social Security, pensions, 401(k) distributions, and capital yields, alongside a 0% state sales tax.
However, you must prepare for significant property taxes. Portsmouth’s citywide revaluation shifted the median assessed single-family home value to $762,600, with typical market sale prices reaching between $800,000 and $890,000.
Portsmouth Regional Hospital operates an accredited Level II Trauma Center directly in town. World-renowned teaching hospitals in Boston sit just sixty minutes south down Interstate 95.
2. Camden, Maine
Camden sits where the rolling Camden Hills meet the deep waters of Penobscot Bay, earning its reputation as a coastal gem.
This harbor community provides paved seaside paths, historic windjammer cruises, and a vibrant public library overlooking an outdoor amphitheater.
Maine provides welcome tax relief for older adults. The state exempts 100% of Social Security Administration (SSA) retirement benefits from state personal income tax.
For tax year 2025, Maine allows retirees to deduct up to $48,216 per person in eligible retirement distributions, reduced dollar-for-dollar by Social Security benefits received.
This deduction begins phasing out for single filers with adjusted gross incomes above $125,000 and married couples above $250,000.
Typical home prices in Camden hover around $575,000, commanding a premium over Maine’s statewide average. Pen Bay Medical Center in neighboring Rockport delivers trusted local care through the MaineHealth network.
3. Mystic, Connecticut
Mystic delivers an authentic maritime environment centered around a historic bascule bridge and the world-renowned Mystic Seaport Museum.
Retirees enjoy scenic waterfront parks, independent shopping districts, and convenient passenger rail service along Amtrak’s Northeast Regional line.
Connecticut has significantly expanded retirement tax exemptions for middle-income seniors. Pension and annuity distributions are 100% exempt from state income tax for single taxpayers earning under $75,000 and married couples under $100,000.
Tax year 2026 marks the complete phase-in of Connecticut’s IRA exemption, allowing qualifying retirees under those same caps to deduct 100% of traditional IRA withdrawals.
Median home prices typically range between $460,000 and $550,000. Keep in mind that Mystic spans two municipalities—Groton and Stonington—each with separate tax rates and assessment schedules.
Regional healthcare is anchored by Lawrence + Memorial Hospital in nearby New London, operating as part of the Yale New Haven Health system.
4. Great Barrington, Massachusetts
Great Barrington serves as the cultural and culinary center of the southern Berkshire Hills in western Massachusetts.
You can attend world-class summer concerts at nearby Tanglewood, view indie films at the Triplex Cinema, and stroll along the Housatonic River.
Massachusetts completely exempts Social Security benefits from state personal income taxes. Other retirement distributions face a flat 5.0% rate, keeping your annual tax filings simple and predictable.
Single-family home prices generally range from $550,000 to over $700,000, with local property tax rates hovering near $13.89 per $1,000 of assessed value.
Healthcare access is an outstanding highlight for this small town retirement New England destination. Fairview Hospital, a federally designated Critical Access Hospital, routinely earns 5-star patient satisfaction ratings from Medicare.gov.
5. Peterborough, New Hampshire
Peterborough provides a tranquil mountain-valley setting surrounded by dense forests, winding rivers, and views of Mount Monadnock.
This historic village inspired Thornton Wilder’s classic play Our Town and hosts the renowned MacDowell artist residency program.
Like Portsmouth, Peterborough provides the unmatched financial advantage of zero state tax on earned income, pensions, and capital gains. New Hampshire’s completed tax phaseout shields your entire investment portfolio from state levies.
Housing here is noticeably more attainable than along the Atlantic coastline. Median sale prices range between $420,000 and $470,000, leaving more capital in your savings.
Monadnock Community Hospital sits directly within town limits, providing 24-hour emergency care, outpatient surgery, and comprehensive physical therapy services.
6. Brunswick, Maine
Brunswick blends coastal proximity with the vibrant intellectual resources of Bowdoin College.
Retirees can audit college classes, explore the Bowdoin College Museum of Art, and attend summer performances at the Maine State Music Theatre.
The town’s downtown Amtrak station allows you to board the Downeaster for easy, car-free day trips to Portland or Boston.
Brunswick residents benefit from Maine’s full Social Security income exemption alongside annual pension deductions up to $48,216 per individual.
Median home values range between $450,000 and $490,000, offering greater purchasing power than many southern Maine coastal towns.
Mid Coast Hospital anchors local wellness, delivering full-service emergency, surgical, and cardiovascular care under the MaineHealth banner.
7. Woodstock, Vermont
Woodstock exemplifies classic Green Mountain beauty with its central village green, covered bridge, and restored Federal-style homes.
Residents enjoy community lectures at the Norman Williams Public Library and seasonal agricultural exhibits at the historic Billings Farm & Museum.
Vermont tax rules require careful planning before you relocate. The state taxes Social Security unless your federal adjusted gross income is $50,000 or less for single filers, or $65,000 or less for joint returns.
Retirement account withdrawals face standard graduated state income tax rates ranging from 3.35% up to 8.75%.
Woodstock real estate carries a premium, with median home prices sitting between $600,000 and $750,000.
However, Woodstock seniors enjoy elite medical care; Dartmouth Hitchcock Medical Center, northern New England’s flagship academic hospital, sits thirty minutes away in Lebanon, New Hampshire.
8. Essex, Connecticut
Essex consists of three historic villages situated along the lower Connecticut River, showcasing preserved eighteenth-century captains’ homes.
You can walk tree-shaded sidewalks to the Connecticut River Museum, watch sailing yachts dock, and dine at the historic Griswold Inn.
Essex retirees benefit from Connecticut’s complete tax exemption on qualifying pension and annuity earnings for households below statutory income limits.
Starting in 2026, you can also withdraw traditional IRA savings tax-free if your adjusted gross income remains under $75,000 (single) or $100,000 (joint).
Typical home prices range from $600,000 to $680,000, reflecting Essex’s quiet waterfront prestige and well-kept public spaces.
For urgent care and outpatient procedures, residents rely on the Middlesex Health Shoreline Medical Center and nearby Yale New Haven facilities.
Comparing Top Retirement Towns in the Northeast
Evaluating where to live requires comparing real estate benchmarks, tax policies, and healthcare networks side by side.
This summary highlights the essential financial and healthcare profiles for each of the eight communities.
| Town & State | Median Home Price | Social Security Tax Status | Retirement Account Treatment | Primary Hospital Network |
|---|---|---|---|---|
| Portsmouth, NH | $800,000–$890,000 | 100% Tax-Free | 0% State Tax (No Income Tax) | Portsmouth Regional Hospital |
| Camden, ME | $575,000 | 100% Tax-Free | Deduction up to $48,216 per person | Pen Bay Medical Center (MaineHealth) |
| Mystic, CT | $460,000–$550,000 | 100% Tax-Free (under income caps) | 100% Exemption for IRAs/pensions under caps (2026) | Lawrence + Memorial (Yale New Haven) |
| Great Barrington, MA | $550,000–$700,000 | 100% Tax-Free | Flat 5.0% State Income Tax | Fairview Hospital (Berkshire Health) |
| Peterborough, NH | $420,000–$470,000 | 100% Tax-Free | 0% State Tax (No Income Tax) | Monadnock Community Hospital |
| Brunswick, ME | $450,000–$490,000 | 100% Tax-Free | Deduction up to $48,216 per person | Mid Coast Hospital (MaineHealth) |
| Woodstock, VT | $600,000–$750,000 | Taxable (Exempt below $50k/$65k AGI) | Taxed at rates from 3.35% to 8.75% | Dartmouth Hitchcock Medical Center |
| Essex, CT | $600,000–$680,000 | 100% Tax-Free (under income caps) | 100% Exemption for IRAs/pensions under caps (2026) | Middlesex Health / Yale New Haven |
Always verify municipal property tax rates and recent assessment dates with the local town assessor before submitting a home offer.
Key Factors to Evaluate Before You Move
Relocating during retirement involves more than admiring autumn foliage or historical architecture.
“A budget isn’t about restriction; it’s about making sure your money supports the life you actually want to live.” — Jean Chatzky, Financial Journalist and Author
Keep these practical elements in mind as you assess charming New England retirement spots:
- Total Tax Exposure: Measure municipal property taxes against state income exemptions rather than focusing on state income tax alone.
- Winter Maintenance Budgets: Budget for professional snow removal, seasonal fuel deliveries, and backup power generator servicing.
- Healthcare Provider Proximity: Ensure primary care physicians and regional specialists accept your specific Medicare coverage or supplemental policy.
- Walkability in Bad Weather: Verify how easily you can navigate sidewalks and access essential pharmacies after significant winter storms.
According to AARP, choosing an age-friendly community with walkable amenities significantly improves long-term health and independence.
Costly Errors to Sidestep
Moving across state lines can trigger surprising costs if you overlook local administrative rules.
Avoid these common mistakes when narrowing down where to retire in New England:
Underestimating Winter Utility Bills
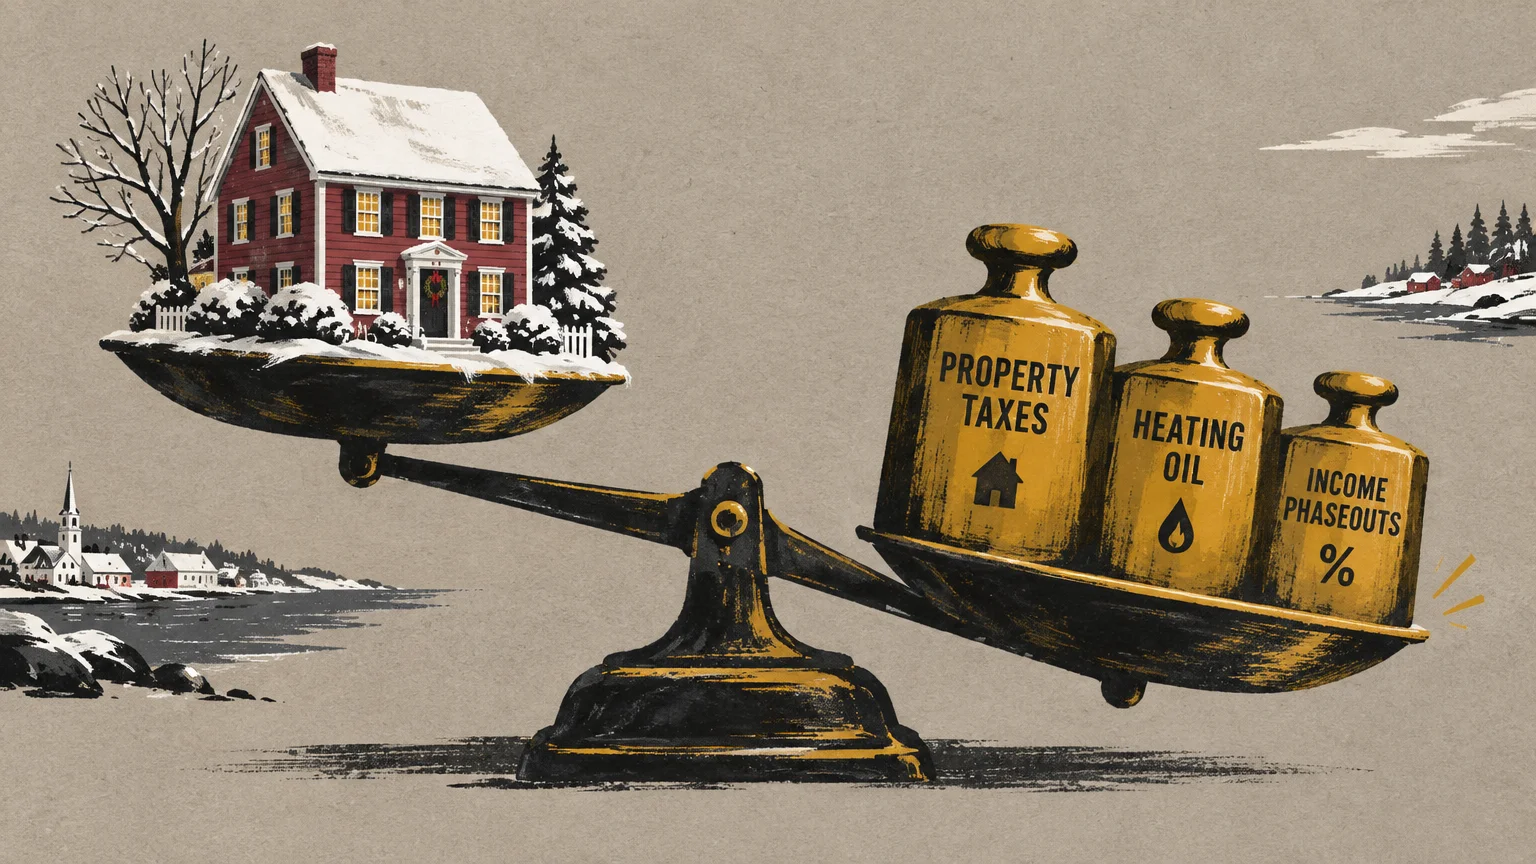
Older New England homes frequently rely on heating oil or propane tanks that experience mid-winter price surges. Failing to evaluate insulation, draft proofing, and furnace age before buying can produce monthly winter heating bills topping $600.
Overlooking Municipal Property Tax Revaluations
States like New Hampshire offset zero income taxes through higher municipal property levies. If you buy right before a scheduled municipal revaluation, your annual property tax bill could jump significantly without warning.
Ignoring Emergency Medical Transit Times
Scenic rural hamlets offer privacy, but they also sit farther from specialized acute care. Failing to map drive times to Level I or Level II trauma centers can leave you vulnerable during medical emergencies.
Assuming Uniform State Tax Treatments
State tax codes vary dramatically across short distances in the Northeast. Assuming your pension or traditional IRA faces identical taxes across state borders can cost you thousands of dollars each year.
Frequently Asked Questions
Which New England state is the most tax-friendly for retirees?
New Hampshire is widely considered the most tax-friendly overall because it levies no state income tax, no sales tax, and no tax on dividends or interest.
However, its property tax rates rank among the highest in the country, meaning retirees with modest pensions may fare better in Maine or Connecticut.
Does Vermont tax Social Security benefits?
Yes, Vermont taxes Social Security benefits for higher earners. Full exemptions apply only to single filers earning $50,000 or less and married couples earning $65,000 or less.
How does Connecticut treat IRA withdrawals in 2026?
Beginning in tax year 2026, Connecticut allows eligible taxpayers to deduct 100% of their traditional IRA distributions from their state income tax returns.
To qualify for this full deduction, your adjusted gross income must remain below $75,000 for single filers or $100,000 for married joint filers.
Does Medicare cover healthcare across New England state lines?
Original Medicare (Part A and Part B) covers medical treatment from any participating physician nationwide regardless of state borders.
If you enroll in a Medicare Advantage plan, you must choose a new plan if your move takes you outside your current provider network.
Next Steps for Your Move
Spend two weeks in your target community during the coldest winter months to experience daily life before committing to a purchase.
Consult a qualified financial planner to model your retirement withdrawals against each state’s tax thresholds and local property tax rates.
This is educational content based on general financial principles for seniors. Individual results vary based on your situation.
Always verify current benefit amounts, tax rules, and program eligibility with official government sources.
Last updated: February 2026. Benefit amounts, tax rules, and program details change annually—verify current figures with official government sources.

Leave a Reply